Risk-Reward Ratio in Trading: The Complete 2026 Master Guide
Risk-reward is the ratio between what a trade can lose and what it can make. This is the complete guide: the math behind 2R, 3R and 4R, how it pairs with win rate, how to calculate it in thirty seconds, and what 10,899 backtest trades show about the reward you plan versus the reward you actually get.
In this article
- What risk-reward ratio actually means
- The math: why 2R changes everything
- How risk-reward pairs with win rate (the expectancy equation)
- How to calculate your R:R in 30 seconds
- What the minimum acceptable risk-reward should be
- Two ways to take profit: the ladder or the whole move
- Calibrating risk-reward for BTC, ETH, SOL and LINK perpetuals
- The 6 ways traders silently destroy their R:R
- Where risk-reward sits inside the CAP Framework
- The R:R you design is not the R:R you get
- Frequently asked questions
What Risk-Reward Ratio Actually Means
Foundation · The Single Most Important NumberThe risk-reward ratio is the ratio between two numbers: how much money you are willing to lose on a trade (your risk) and how much money you are trying to make (your reward). Both numbers are defined before the trade is taken, not during, not after, not based on how the trade feels mid-flight. They are written down before any order is placed.
If your stop is $100 below your entry on a long, your risk is $100. If your target is $300 above your entry, your reward is $300. The risk-reward ratio is $300 ÷ $100 = 3. That trade is a 1:3 risk-reward: risk one unit to make three.
Most professional traders simplify this further by talking in "R" units. 1R is your risk. Always. Whether you are risking $50 or $50,000, your defined risk on that single trade is 1R. A target at 2R is twice your risk in profit. A target at 4R is four times your risk in profit. A trade that hits its stop is a −1R outcome. A trade that hits a 3R target is a +3R outcome. This is the language of every professional trading desk and every serious trading system on earth.
Why R-units instead of dollars? Because they make the math comparable across position sizes, account sizes, time periods, and even different markets. A 60% win rate at +2.5R blended is the same edge whether the trader is risking $10 a trade or $10,000 a trade. The dollars change. The R math does not.
R:R in 15 Seconds
Decide how much you are willing to lose before you enter. That amount is 1R. Decide where the price needs to go to make the trade worthwhile. If the target is twice as far as the stop, you are taking a 2R trade. If it is three times as far, it is a 3R trade. Higher R per trade means you can survive more losing trades and still be profitable.
The Math: Why 2R Changes Everything
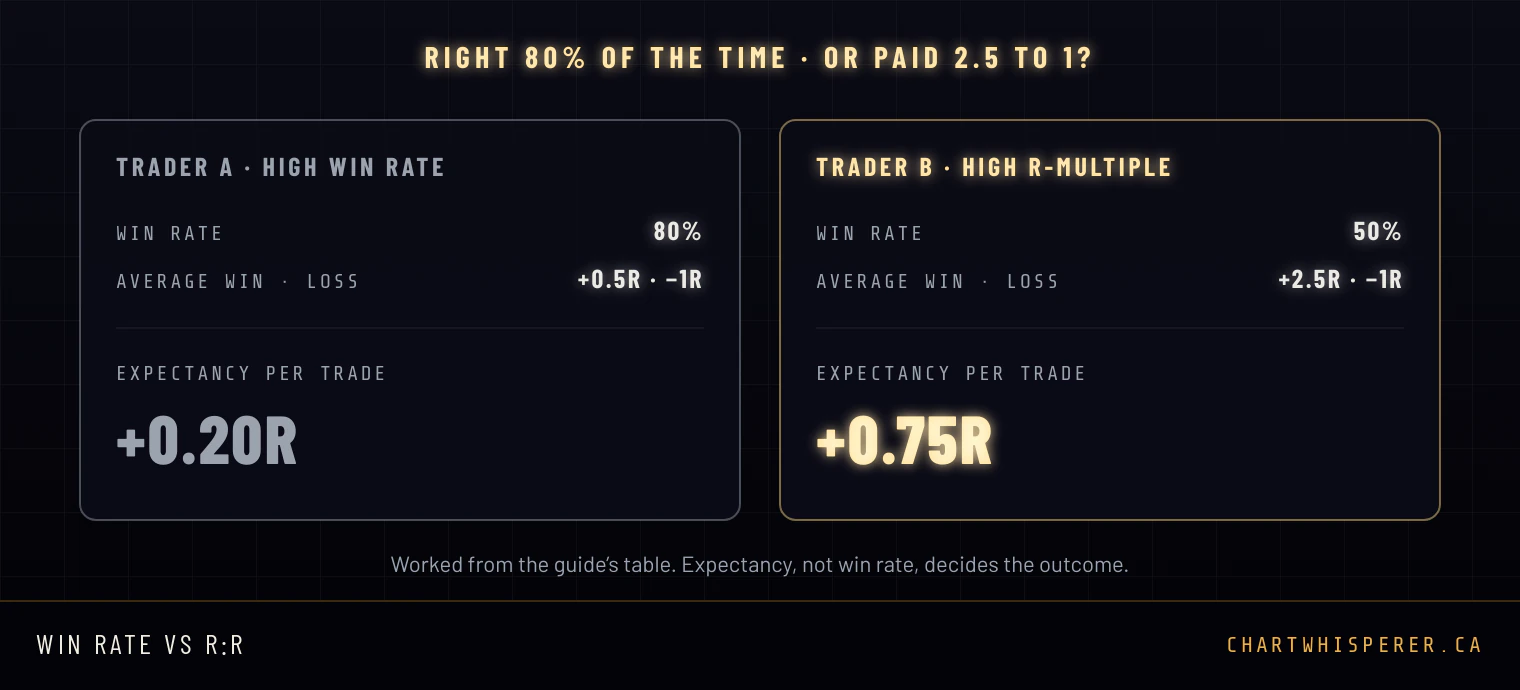
The Equation · Why R:R Beats Win RateMost beginner traders chase a higher win rate. They want to be right more often because being right feels good. This pursuit is the single biggest cause of long-term unprofitability in retail trading, because the math of an edge does not care about feelings. It cares about expectancy.
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
Consider two traders:
| Trader | Win Rate | Avg Winner | Avg Loser | Expectancy per Trade |
|---|---|---|---|---|
| Trader A: High Win Rate | 80% | +0.5R | −1R | (0.80 × 0.5) − (0.20 × 1) = +0.20R |
| Trader B: High R-Multiple | 50% | +2.5R | −1R | (0.50 × 2.5) − (0.50 × 1) = +0.75R |
Trader A is right 80% of the time. Trader B is right exactly half the time. Trader B makes nearly four times more money per trade. Across a hundred trades risking 1% per trade, Trader A produces +20% expected return. Trader B produces +75%. This is the math that breaks the intuition of every new trader.
It is also why every serious trading framework, from Mark Douglas’s Trading in the Zone to the systematic prop desks of Renaissance and Two Sigma, places R-multiple optimisation ahead of win-rate optimisation. Win rate is a feeling. R-multiple is an edge.
"Anyone who is not embarrassed by their old code (or their old trades) has not learned anything."
Adapted from Alan Kay — applied to traders by Mark Douglas
How Risk-Reward Pairs With Win Rate (The Expectancy Equation)
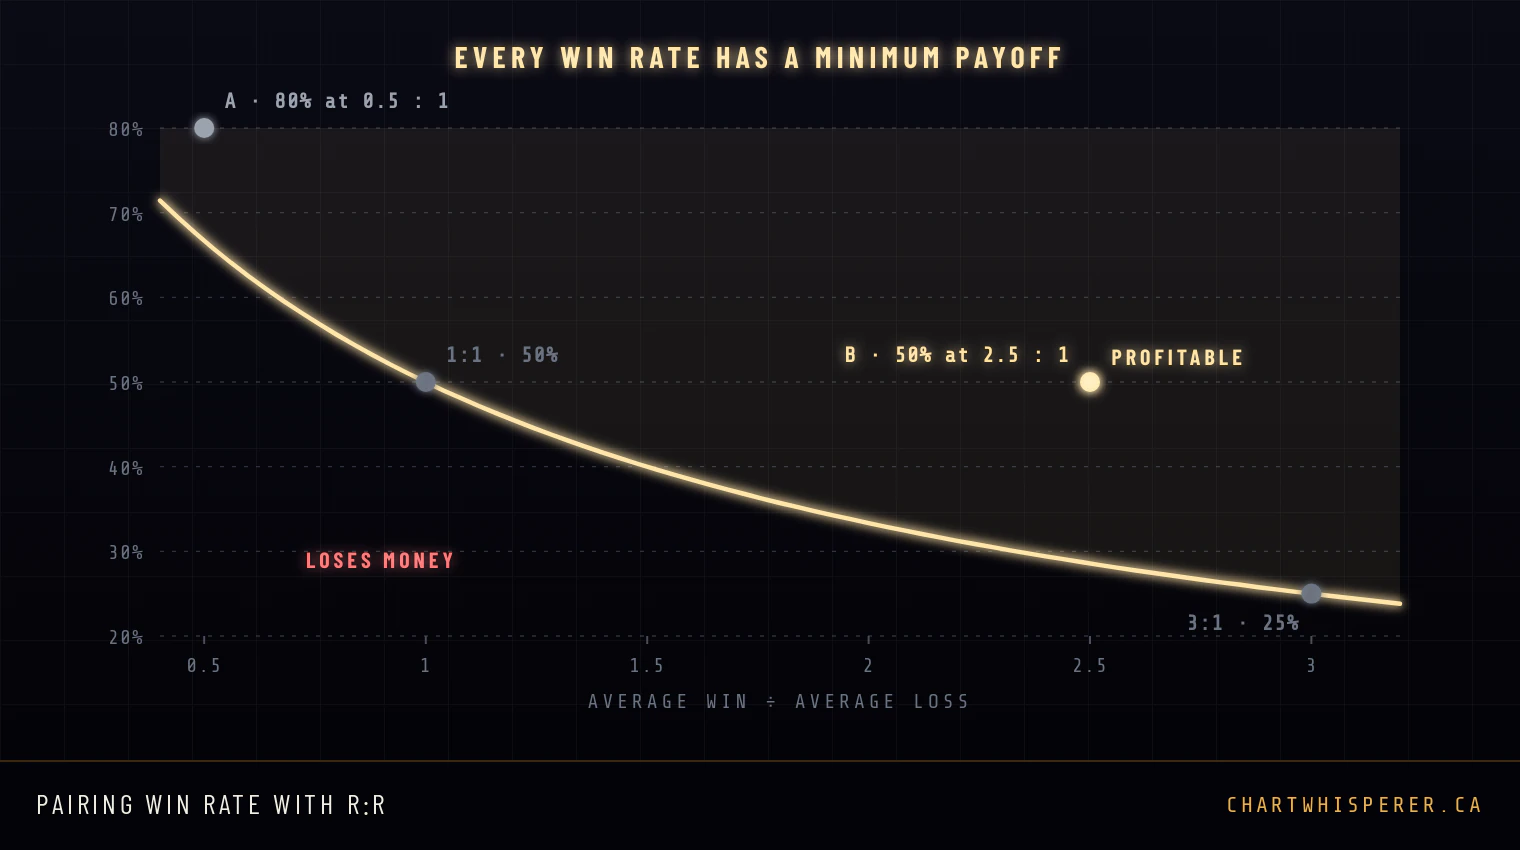
The Combined Math · Win Rate Required for Each R:RRisk-reward and win rate are two sides of the same equation. Neither matters in isolation. The single most useful piece of math any trader can memorise is the break-even win rate required for each common R:R, because it tells you exactly how often you need to be right to make money.
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
| Risk-Reward Ratio | Win Rate Needed to Break Even | Win Rate for Solid Profitability (1.5× break-even) |
|---|---|---|
| 1:1 | 50% | ~67% |
| 1:1.5 | 40% | ~55% |
| 1:2 | 33% | ~45% |
| 1:2.5 | 29% | ~40% |
| 1:3 | 25% | ~35% |
| 1:4 | 20% | ~28% |
| 1:5 | 17% | ~24% |
What this table actually says is profound. At a 1:3 risk-reward, you only need to be right 25% of the time to break even, meaning you can be wrong three-quarters of the time and still keep your money. Anything above 35% becomes solidly profitable. This is the freedom that R-multiple gives you: room to be wrong without being ruined.
At a 1:1 ratio, on the other hand, you need to be right at least half the time just to break even, and at 67% to be solidly profitable. Sustaining a 67% win rate over hundreds of trades requires near-perfect execution, ideal market conditions, and no psychological errors. It is brutally hard. This is why so few traders survive at low R:R ratios.
The 8-Point Setup Gate Checklist
Everything below this line gets easier once you trade behind a fixed pre-trade filter. This is the exact 8-point checklist used to grade every BTC, ETH, SOL and LINK setup. Free, by email, about a minute to read.
How to Calculate Your R:R in 30 Seconds
Practical · The Calculation in Live TradingThe risk-reward calculation is simple division. The discipline is doing it before the trade, on every trade, every time.
Decide the exact price you intend to enter at. Not "around here". A specific number. For a limit order, this is the order price. For a market entry, this is the current price.
Decide the exact price at which the trade is invalidated and you are out. For longs, this is below the most recent swing low or below the FVG mitigation, plus your buffer. The distance from entry to stop = your risk in dollars (or in pips, or in basis points).
Decide the exact price you are aiming for. For most retail traders, this is the next obvious resting liquidity pool: a recent swing high, an old session extreme, or a key Fibonacci level. The distance from entry to target = your reward.
If reward ÷ risk is less than 2, the trade does not qualify. Either find a better entry or pass on the setup. The minimum acceptable R:R is the gate that filters bad trades before they happen.
What the Minimum Acceptable Risk-Reward Should Be
The Filter · The Minimum That Makes Math WorkDifferent trading styles support different minimum risk-reward ratios. The minimum that works for a scalper trading 50+ trades a week is different from the minimum that works for a swing trader taking three setups a month. That said, there are some hard mathematical floors that apply regardless of style.
| Trading Style | Minimum R:R | Typical Win Rate | Why |
|---|---|---|---|
| Scalping (multiple trades per session) | 1:1.5 | 60–70% | High win rate offsets lower R-multiple. Volume of trades produces the edge. |
| Intraday systematic (5–15 trades per week) | 1:2 | 55–65% | The sweet spot for most retail BTC and ETH perpetuals traders. Best balance of frequency, accuracy, and edge. |
| Swing (2–5 trades per week) | 1:3 | 45–55% | Larger targets mean lower hit-rates. R-multiple has to compensate. |
| Positional (1–3 trades per month) | 1:5+ | 40–50% | Massive targets across multi-day or multi-week holds. The edge comes from outsized winners covering many small losers. |
The CAP Framework on this site sits in the last row, and then some: it sets no target at all and holds the whole position until the bigger move ends. In its backtest the average win was +4.19R and the average loss −0.80R, a payoff of about 5.2 to 1, which puts its break-even win rate near 16%. S and A grade setups actually won 78.6% of 10,899 trades (backtest of S and A grade setups, after all costs, on modelled versions of Charles’s calls, not account statements). The high win rate comes from selectivity (only top-graded setups, with the trend, about ten a year on each coin), not from small targets.
Two Ways to Take Profit: The Ladder or the Whole Move
Execution · Turning Theoretical R:R Into Realised R:RThere is a quiet but enormous difference between theoretical R-multiple (what the trade would produce if you held to a single target) and realised R-multiple (what you actually keep when the trade closes). Traders bridge that gap in one of two ways.
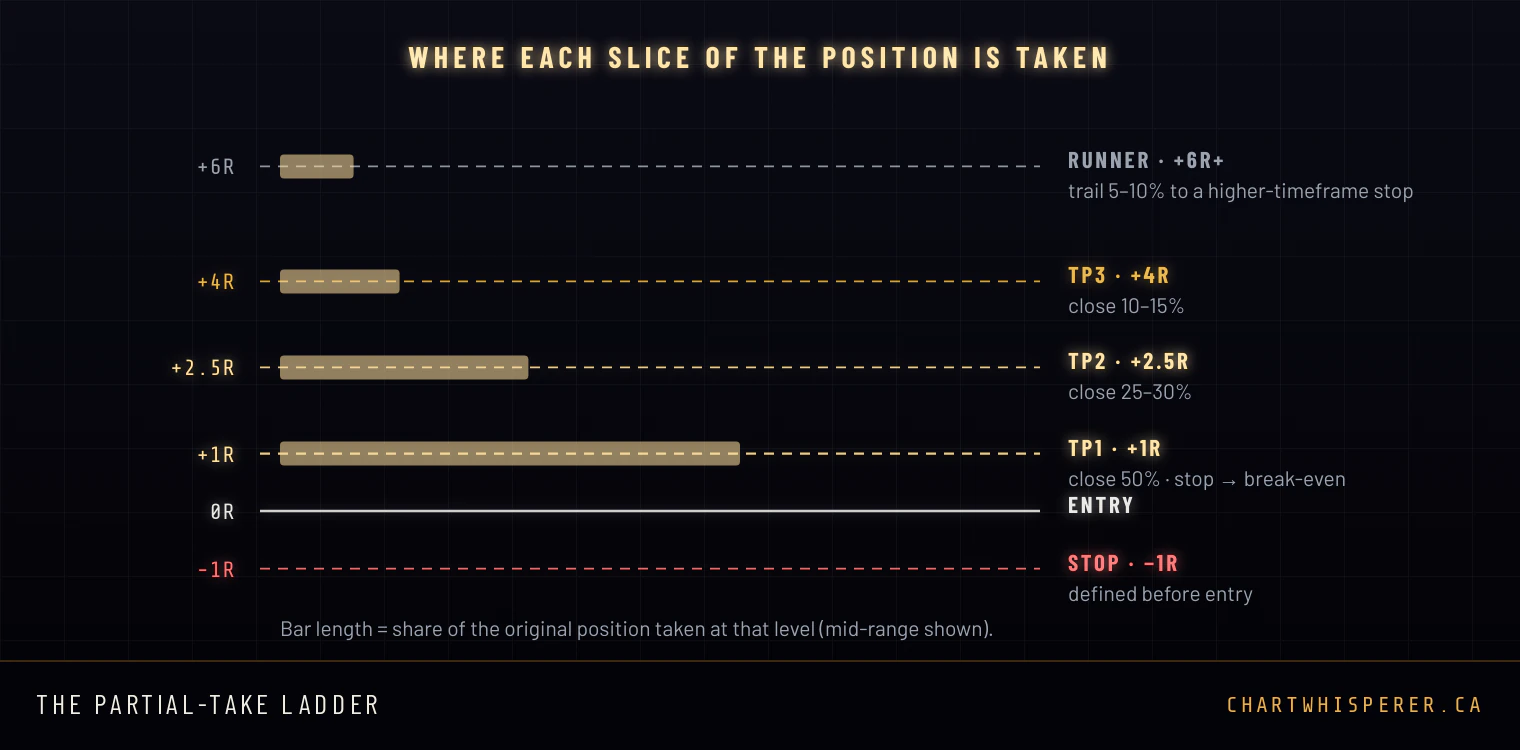
1. The partial-take ladder
The ladder is the most common approach in discretionary trading: bank part of the position at the first target, move the stop to break-even, and let smaller pieces aim further away.
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
| Level | R-Multiple | Action | What it buys you |
|---|---|---|---|
| TP1 | +1R | Close 50% of the position | Something banked early, at the level price reaches most often. |
| Breakeven move | at +1R | Move stop to entry price | Less stress on the rest, at the cost of being shaken out by normal pullbacks. |
| TP2 | +2.5R | Close 25–30% of the original position | The main move, on a shrinking position. |
| TP3 / runner | +4R and beyond | Close or trail the last 15–25% | A small piece left for the outsized move. |
The ladder’s strength is psychological: it pays you something on most trades. Its weakness is mathematical. The trades that run furthest are the ones that pay for everything else, and the ladder has sold most of the position long before they get there. The break-even stop adds a second cost: a normal pullback closes the rest for nothing, often just before the move continues.
2. Hold the whole position until the bigger move ends
The CAP does the opposite. Once the five gates pass, the stop sits beyond the last 4-hour swing plus a small buffer, the size comes from that stop, and the whole position is held until the bigger move ends, capped at 120 days in testing. No targets, no partial profits, no stop moved to break-even, no adding. Backtested on 10,899 S and A trades, the average win was +4.19R, and nearly a quarter of all trades (23.8%) reached +4R or more. 7.1% reached +10R. The median trade, +1.53R, is far below the average because a minority of very large winners carry the total, exactly the trades a ladder would have cut short.
Calibrating Risk-Reward for BTC, ETH, SOL and LINK Perpetuals
Cross-Asset · The Real Numbers Per MarketDifferent assets need different stop distances because their volatility is different. The R math stays identical. What changes is the percentage distance from entry that 1R represents. The CAP builds that into its rules: the break of structure must be larger, and the stop buffer wider, on the more volatile coins. Here is what that looked like in its backtest.
| Coin | BOS needed | Stop buffer | Median stop distance | Average trade |
|---|---|---|---|---|
| Bitcoin | 2% | 0.3% | about 5.0% | +3.28R (n=3,031) |
| Ethereum | 2% × 1.35 | 0.45% | about 6.0% | +3.16R (n=2,981) |
| Solana | 2% × 1.98 | 0.6% | about 8.5% | +3.14R (n=2,026) |
| Chainlink | 2% × 1.74 | 0.52% | about 8.0% | +2.91R (n=2,861) |
Two things follow. First, the stop is wide in price terms (several percent, not a few tenths), so the position is smaller, and leverage is an output of the plan, not an input. Second, the R-multiple evens out across coins: Solana’s wider stop is matched by wider moves, which is why its average trade sits close to Bitcoin’s even though it won less often (74.2% against 80.1%). These are backtest figures, after all costs; past performance does not guarantee future results.
Intraday traders work with much tighter stops, a few tenths of a percent on Bitcoin, and correspondingly smaller targets. The same R math applies. The noise is larger relative to the stop, so the win rate is usually lower. The CAP itself, traded on lower timeframes, takes more trades with a lower win rate and a smaller reward per trade.
The 6 Ways Traders Silently Destroy Their R:R
Common Failures · How the Math Collapses in PracticeThe math of risk-reward is bulletproof on paper. In practice, retail traders systematically destroy it through six predictable behaviours. Each one is a deviation from the protocol that turns a 1:3 theoretical trade into a 1:0.8 realised trade or worse.
| The Mistake | What Happens to R:R | The Fix |
|---|---|---|
| 1. Closing winners early | Realised R collapses. The big winners that pay for the losers never arrive | Let the written rule close the trade. In the CAP the whole position is held until the bigger move ends. |
| 2. Moving the stop to give losers "more room" | 1R loss balloons to 2R, 3R, or full account drawdown | Stop is defined at entry. Never widen. If structure breaks, the trade was invalid. |
| 3. Adding to losing positions ("averaging down") | Total risk doubles or triples while target stays the same. R:R inverts to 2:1 risk vs reward | Never add to a loser. The system is designed around fixed-size entries. |
| 4. Taking trades the plan does not allow | The edge was measured on the setups the rules allow. Everything else is an untested system | Every gate or no trade. In the CAP, only S and A grade setups are taken. |
| 5. Dragging the stop to break-even | Normal pullbacks close trades for nothing just before they run. The large winners disappear | Leave the stop where the idea is wrong. In the CAP it never moves. |
| 6. Inconsistent position sizing | One trade risks 0.5%, the next risks 2%. R math becomes meaningless across the sample. | Same risk percentage on every single trade. Always. The math only works if the position-sizing input is constant. |
Where Risk-Reward Sits Inside the CAP Framework
Integration · Points 7 and 8 of the ChecklistIn the CAP, risk-reward is not a gate you check at the end. It is built into the last two points of the 8-point checklist that wraps the five gates: stop and size, then hold. The trade first has to pass the regime, a strong break of structure, the pullback to the OTE zone (0.382 to 0.236 on the inverted Fibonacci, sweet spot 0.295), an S or A confluence grade, and the CHoCH close. Only then do the risk numbers come in.
The stop goes beyond the last 4-hour swing plus a buffer for the coin’s volatility. The size is your fixed risk divided by that distance. And the reward is never capped: the whole position is held until the bigger move ends. That is why the CAP’s average win, +4.19R, is so much larger than the targets most traders set, and why its average loss is only −0.80R: stopped trades averaged about −1.1R after costs, while 835 trades that ran to the end of the move finished slightly below zero.
These are backtest of S and A grade setups, after all costs, on modelled versions of Charles’s calls, not account statements. The direction of each trade is Charles’s call, and the same entries with a mechanical direction showed no edge. Past performance does not guarantee future results.
The Complete R:R Discipline in One Line
Define risk before entry, size from the stop, never widen it, never drag it to break-even, never add to a loser, and let the written rule, not the feeling, decide when the trade ends.
The R:R You Design Is Not the R:R You Get
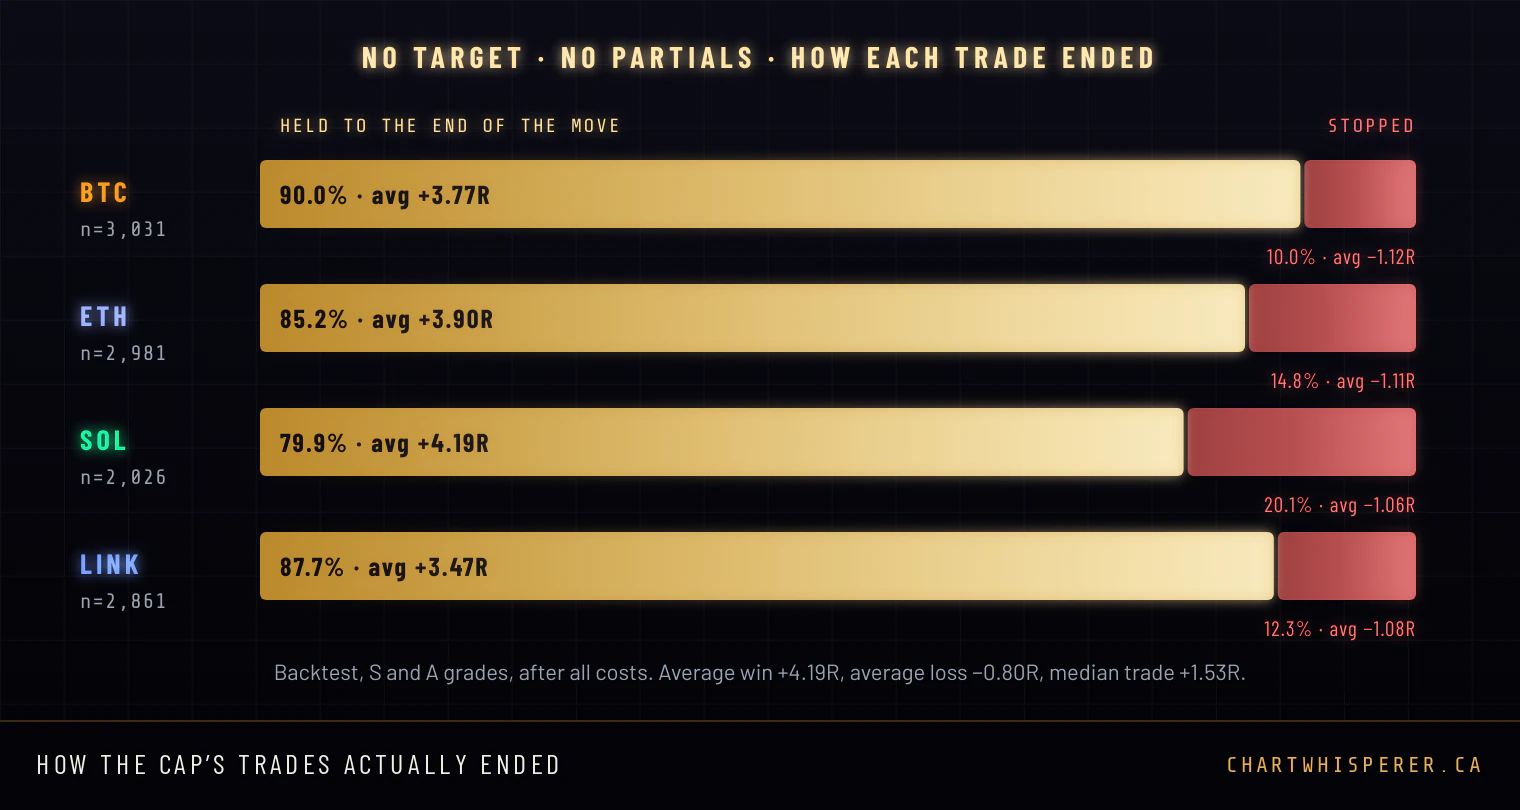
First-Party Data · Where Trades Actually EndedA plan is a plan. What a strategy actually returns is decided by how its trades end, and most risk-reward writing never shows that. Here it is for the CAP, measured on all 10,899 trades in its backtest.
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
| How the trade ended | BTC (n=3,031) | ETH (n=2,981) | SOL (n=2,026) | LINK (n=2,861) |
|---|---|---|---|---|
| Held to the end of the bigger move | 90.0% · avg +3.77R | 85.2% · avg +3.90R | 79.9% · avg +4.19R | 87.7% · avg +3.47R |
| Stopped (after costs) | 10.0% · avg −1.12R | 14.8% · avg −1.11R | 20.1% · avg −1.06R | 12.3% · avg −1.08R |
Without a target, there is no “designed” R to inflate. The trade ends when the bigger move ends, and the R is whatever that move paid. That produced a wide spread of outcomes: 59.1% of trades reached +1R or more, 32.0% reached +3R, 7.1% reached +10R, and 835 trades ran to the end of the move but still finished at or just below zero after costs. The average win, +4.19R, is the honest summary of that spread. The median trade, +1.53R, is the typical one.
This is a backtest of S and A grade setups, after all costs, on modelled versions of Charles’s calls, not account statements. Past performance does not guarantee future results. The full tables, the weak years and the losing stretches are published on Protocol Results.
Frequently Asked Questions
What is the risk-reward ratio in trading?
The risk-reward ratio (R:R, or sometimes reward-to-risk ratio) is the comparison between how much you are willing to lose on a trade and how much you are aiming to make. If your stop is $100 below your entry and your target is $200 above your entry, your risk-reward ratio is 1:2 — you are risking one unit to make two. Most professional traders express this in "R" terms: 1R is your risk, 2R is twice your risk in profit, 3R is three times your risk, and so on. The ratio is set before the trade is taken and is one of the only two variables (alongside position size) you have complete control over. It is the single most important number in trading mathematics because it determines whether you can profit even at a relatively low win rate.
What is the best risk-reward ratio for crypto trading?
A 1:2 risk-reward ratio is the widely cited minimum because it lets you be profitable at any win rate above about 34% (before fees and slippage). For a trader using fixed targets, 1:2 to 1:3 is the practical range; going much higher on every trade lowers the hit rate. The other approach is to set no target and hold the whole position until the bigger move ends, as the CAP does: in its backtest of S and A grade setups, after all costs, that produced an average win of +4.19R against an average loss of −0.80R, with 78.6% of 10,899 trades won. That is a modelled backtest, not an account statement, and past performance does not guarantee future results.
How do you calculate the risk-reward ratio?
Risk-reward calculation is simple division. Define entry price, stop price, and target price before the trade. Risk = entry − stop (for a long). Reward = target − entry (for a long). Ratio = reward ÷ risk. Example on BTC: entry at $68,000, stop at $67,500 (risk = $500), target at $69,500 (reward = $1,500). Risk-reward = $1,500 ÷ $500 = 3, a 1:3 trade. For a short, flip the subtraction direction. This calculation is independent of position size. A 1:3 trade is a 1:3 trade whether you are risking $50 or $5,000. Position size is a separate (equally important) variable determined by what percentage of your account you are willing to risk per trade, typically 1% for most retail accounts.
Can you be profitable with a 1:1 risk-reward ratio?
Technically yes, at a sustained win rate above 50% (after fees and slippage). In practice, the vast majority of traders who attempt to trade 1:1 fail because the win rate required is brutal to sustain over hundreds of trades, the math leaves no room for variance, and the small reward-per-trade means commissions and funding costs eat a meaningful share of profit. Across thousands of documented retail trading accounts, the failure rate at 1:1 R:R is dramatically higher than at 1:2 or 1:3, not because 1:1 cannot mathematically work, but because the discipline and edge required to sustain a 55%+ win rate trade after trade are rare. The asymmetric risk-reward approach (risk less, aim for more) gives you mathematical room for losing streaks, which always come, and is the path most professional systematic traders take.
What does R-multiple mean in trading?
R-multiple is a way of expressing trading results in units of risk rather than dollars. If you risk $100 on a trade (your defined risk = 1R) and you make $300, that trade was +3R. If you lose $100 (the stop hits), that trade was −1R. Expressing results in R rather than dollars makes performance comparable across position sizes, account sizes, and time periods. It also makes the math of edge transparent: an edge that produces an average of +0.5R per trade across 100 trades is worth roughly 50% of your initial risk-bank in cumulative R, which compounds extraordinarily over a long enough series. R-multiples are how every professional trader and every serious trading system describes results internally. Dollars are the output. R is the input you actually control.
How does risk-reward pair with win rate (the expectancy equation)?
The expectancy equation is the single most important formula in trading: Expectancy = (Win Rate × Average Win) − (Loss Rate × Average Loss). Expressed in R terms with consistent 1R risk: Expectancy per trade = (Win Rate × Average R Per Winner) − (Loss Rate × 1R). A system with a 60% win rate and an average winner of 2R produces: (0.60 × 2) − (0.40 × 1) = 1.2 − 0.4 = +0.8R per trade. A system with an 80% win rate but only 0.5R average winner produces: (0.80 × 0.5) − (0.20 × 1) = 0.40 − 0.20 = +0.2R per trade. The 60% / 2R system is four times more profitable per trade than the 80% / 0.5R system, despite a much lower win rate. This is why chasing higher R-multiples beats chasing higher win rates. Risk-reward and win rate are two sides of the same equation, and you cannot evaluate either in isolation.
Is a 3:1 risk-reward ratio realistic?
A 3:1 reward-to-risk ratio (often written 1:3 risk-reward) is realistic as an average, but not on every trade: the further away a target is, the less often price reaches it before the stop. One option is a partial-take ladder, which banks something early at the cost of cutting the biggest winners. The other is to set no target and let the bigger move decide. In the CAP backtest, 32.0% of 10,899 trades reached +3R or more and the average win was +4.19R, after all costs, because the whole position was held until the move ended.
What does 2R or 3R mean in trading?
R is the amount you risk on one trade: the distance to your stop multiplied by your position size. 2R is a gain of twice that amount and 3R three times. If you risk 2% of your account and the trade makes 2R, you gain 4%. At 3R you gain 6%. A full stop-out is -1R. Writing results in R lets you compare trades of any size.
What win rate do you need at 2R or 3R to break even?
Before costs, the break-even win rate is 1 divided by (1 + R): 50% when the win equals the risk, 33.3% at 2R, 25% at 3R and 20% at 4R. Above that rate you make money over many trades. Below it you lose. Fees, funding and slippage push the real figure higher, most of all on short timeframes, where costs are a bigger share of each trade.
Knowing the math is one thing. Building it into the trade is everything.
The CAP builds the math in: a stop beyond the last 4-hour swing, size from that stop, and the whole position held until the bigger move ends. No targets, no partials, no break-even stop. See the decision engine built around that math.
Explore the CAP Framework →Prefer to start free? Take the Free 6-Day Course →
Want a live walkthrough? The 90-Day Mentorship →
The Chart Whisperer · chartwhisperer.ca · All prices in USD.