Money Management & Risk Control
You can read the chart perfectly and still lose the account. Most accounts do not end because of one bad call. They end because too much money was riding on each trade when a run of losses arrived, and a run of losses always arrives. This guide shows you, in plain numbers and pictures, how much to put on each trade so the bad weeks cost you a little and never everything.
New here? Start with this
The eight words this page runs on
No trading background needed. Every idea below is explained in plain English first, with a picture, and then in the detail an experienced trader expects. These are the only terms you need before you start.
- Stop
- The price where you accept the trade idea was wrong and get out. It is chosen before you enter, never during the trade.
- R
- The amount you lose if your stop is hit. Every result on this page is measured in it, so +2R means you made twice what you risked.
- Position size
- How much you buy or sell. It is worked out from your stop and your risk, not from how confident you feel.
- Leverage
- Borrowing from the exchange to open a position bigger than the cash you put down. It changes the cash needed, not the loss at your stop.
- Win rate
- The share of your trades that make money. On its own it tells you almost nothing, because it ignores how big the wins and losses are.
- Drawdown
- How far the account has fallen from its highest point. A drawdown of 20% means you are 20% below your best balance.
- Expectancy
- The average result per trade, in R, once every win and loss is counted. Positive expectancy is what makes a strategy worth trading.
- Backtest
- Running a strategy's exact rules over past price data to see what they would have done. Useful, but live results are usually worse.
Defense first.
Offense second.
In plain EnglishHow much you put on each trade matters more than how good your entries are, because a run of losing trades is guaranteed sooner or later. Size decides whether that run is a scratch or the end of the account.
Ask a room of new traders what they need to improve and they say their entries. Ask a room of professionals and they say their risk. The difference is not temperament. It is arithmetic. Losing streaks are certain over a large enough sample, and the only thing that decides whether a streak is a scratch or a funeral is how much was riding on each trade before it started.
This is the fifth pillar, and in a real sense the one the other four stand on. Wyckoff, Elliott Wave and Order Flow find the trade. Psychology lets you take it. Money management decides whether the account is still here next month, and it does that by answering one question on every trade: how much.
It is also where most accounts actually end. On the prop firm statistics page, roughly 71% of first-phase challenge failures are daily drawdown breaches. Not a bad read of the chart. A position sized so that one bad morning was allowed to be fatal.
This guide works through the whole survival layer in the order you need it: the units, the expectancy, the sizing, the streaks, the drawdowns, and the rules that keep a normal losing run from becoming a permanent one. Where a number comes from the published CAP backtest, it is the backtest as it stands on /protocol-results, with its sample size and its drawdown attached. The ugly numbers are in here on purpose.
In the CAP Framework the stop is structural. It sits where the setup is invalidated, not where it feels comfortable. Because that distance is known the instant Gate 5 closes, size is arithmetic: a fixed fraction of equity divided by the stop distance. There is no moment left in which to negotiate with the trade.
That is the real job of a mechanical system. It turns money management from a test of willpower you will eventually fail into a calculation you cannot skip.
Size a Trade Now→ See the Published BookR
THE UNIT THAT MAKES TRADES COMPARABLE
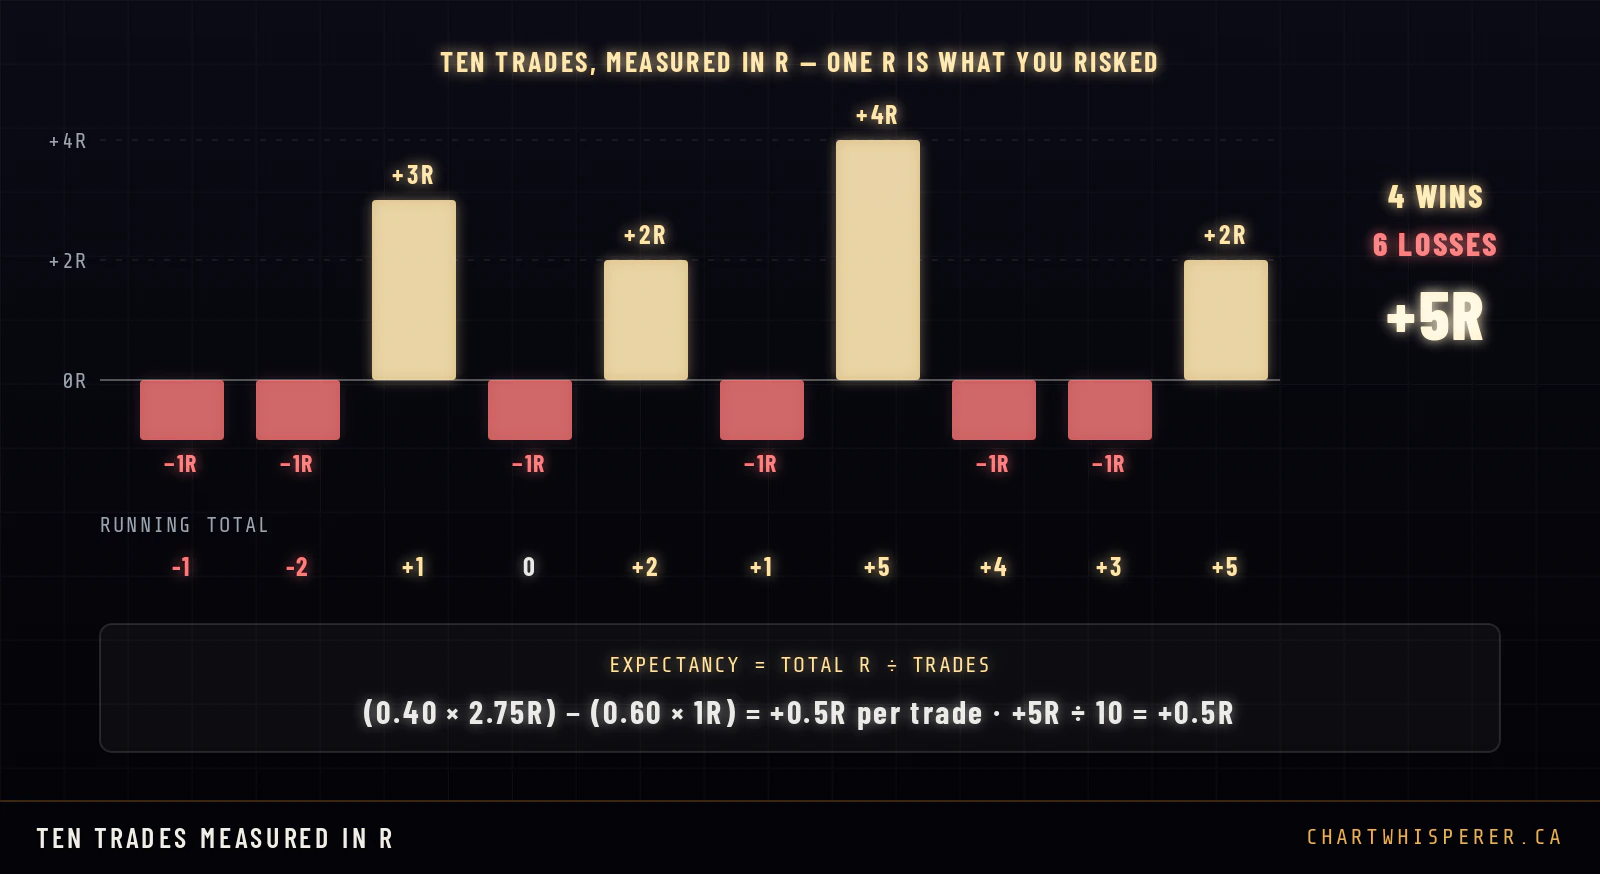
In plain EnglishMeasure every trade against the amount you risked on it. Risk $100 and make $200, that is +2R. Lose the $100, that is −1R. Now a small account and a large one can be compared fairly.
Stop thinking in dollars. One R is what you stood to lose when you entered: the distance from entry to stop, times your size. Risk $100 and make $300 and that is a +3R trade. Get stopped for the full $100 and it is −1R. Measured in R, a trade on a $2,000 account and a trade on a $2,000,000 account read the same, which is the whole point.
Van Tharp popularised the idea, and it does two jobs at once. It separates the quality of a system from the size of the bet, so you can judge the edge without the account balance shouting at you. And it makes the one number that decides everything, expectancy, a single line of arithmetic.
A trade that closes somewhere in between gets a fractional R. Close half at 1R and scratch the rest at break-even and the trade paid +0.5R. Slippage through your stop on a fast candle and the loss prints −1.2R. Costs count too, and they are charged in R, which matters more than most traders realise. That is its own chapter further down.
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
EXPECTANCY
WHAT ONE MORE TRADE IS WORTH
In plain EnglishExpectancy is what one trade is worth on average once all the wins and losses are added up. If it is above zero, the strategy makes money over many trades. If it is below zero, nothing else can save it.
Expectancy is the average R a system earns per trade across a large sample. Positive, and every trade you take is worth something before it starts, even the ones that lose. Negative, and no amount of discipline, psychology or position sizing will save the account. It only decides how slowly it goes.
Expectancy = (win rate × average win in R) − (loss rate × average loss in R)
Notice what is not in the formula. Win rate alone is not there, and neither is the biggest winner you ever had. A system can win 40% of the time and make money if its wins are large enough, and a system can win 70% of the time and bleed if its losses are larger still. The two halves only mean something together.
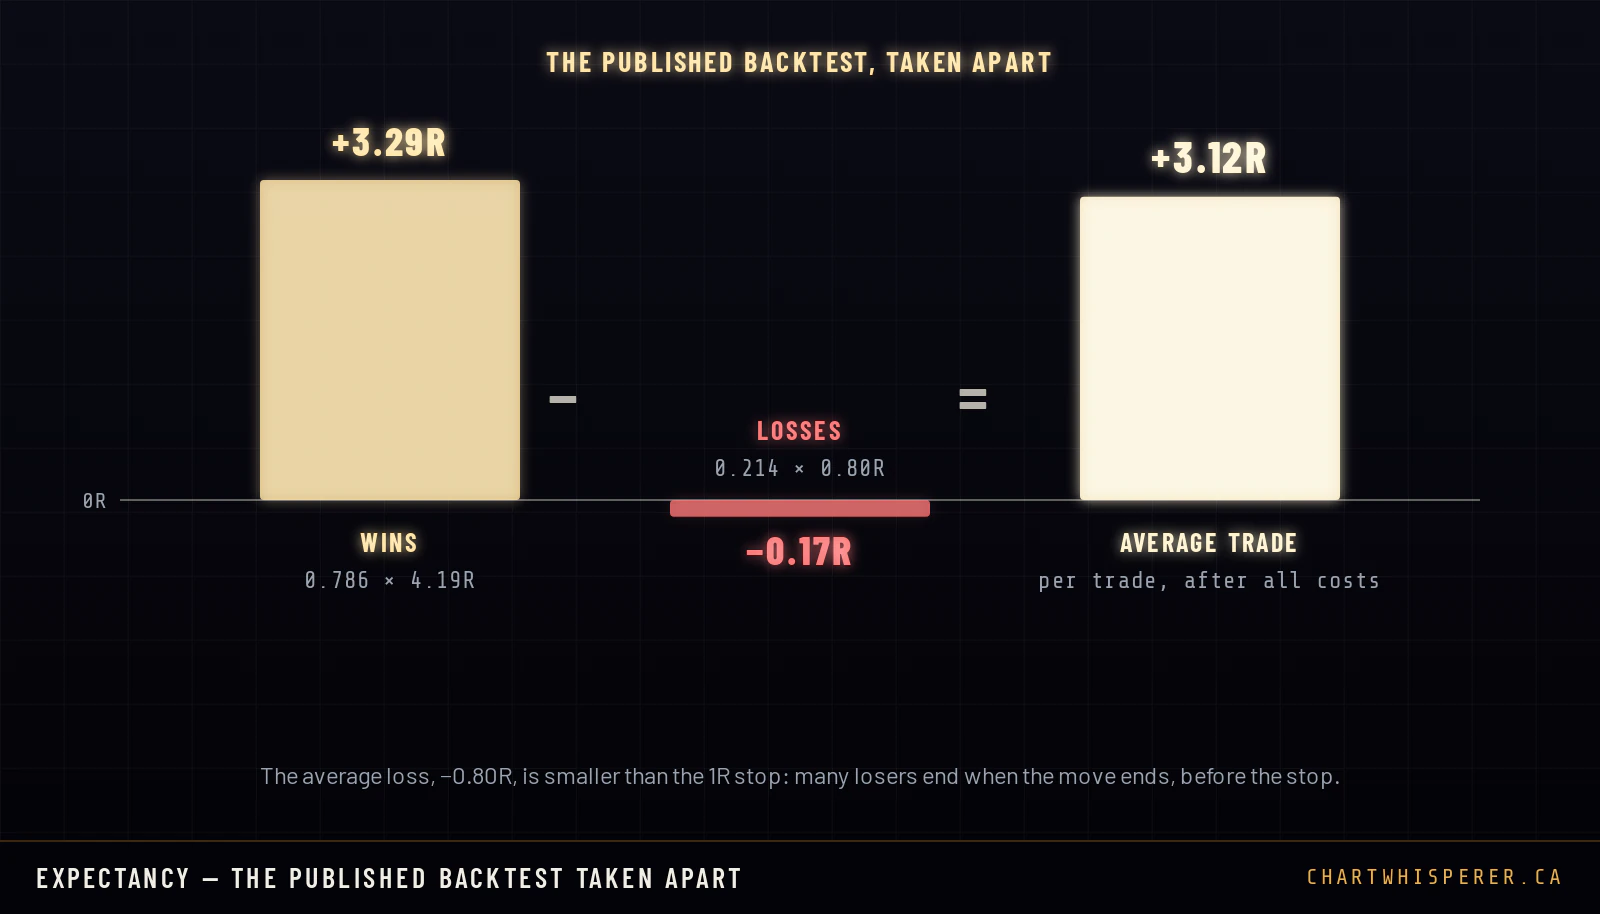
Here is the published CAP backtest taken apart the same way, because a formula is easier to trust when you can watch it resolve on real figures. Across four coins and 10,899 S and A grade backtest trades, after every cost, 78.6% finished in profit. The average win across the 8,562 winners was +4.19R. The average loss across the 2,337 losers was −0.80R.
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
That last point is the one most trading education skips, so it is worth sitting on. A high win rate with a payoff below 1:1 is a legitimate edge, and so is a low win rate with a payoff of 3:1. They feel completely different to trade. The first wins most days and occasionally takes a loss that erases three wins. The second loses most days and occasionally pays for a month. Neither is better. What matters is that you know which one you are running, because the emotional failure mode of each is different.
Two more measures sit next to expectancy and are worth knowing by name. Profit factor is gross R won divided by gross R lost. In the CAP backtest it is about 19 (10,899 trades, S and A grades, after all costs), because the average win was about five times the average loss and only about one trade in five lost. System quality, Van Tharp's SQN, is expectancy divided by the standard deviation of R, times the square root of the number of trades. It rewards a smooth edge over a lumpy one, which is exactly what a trader who has to live through the equity curve should want.
WIN RATE vs PAYOFF
THE BREAKEVEN FRONTIER
In plain EnglishThe less often you win, the bigger your wins have to be. This chart shows exactly how big, for any win rate.
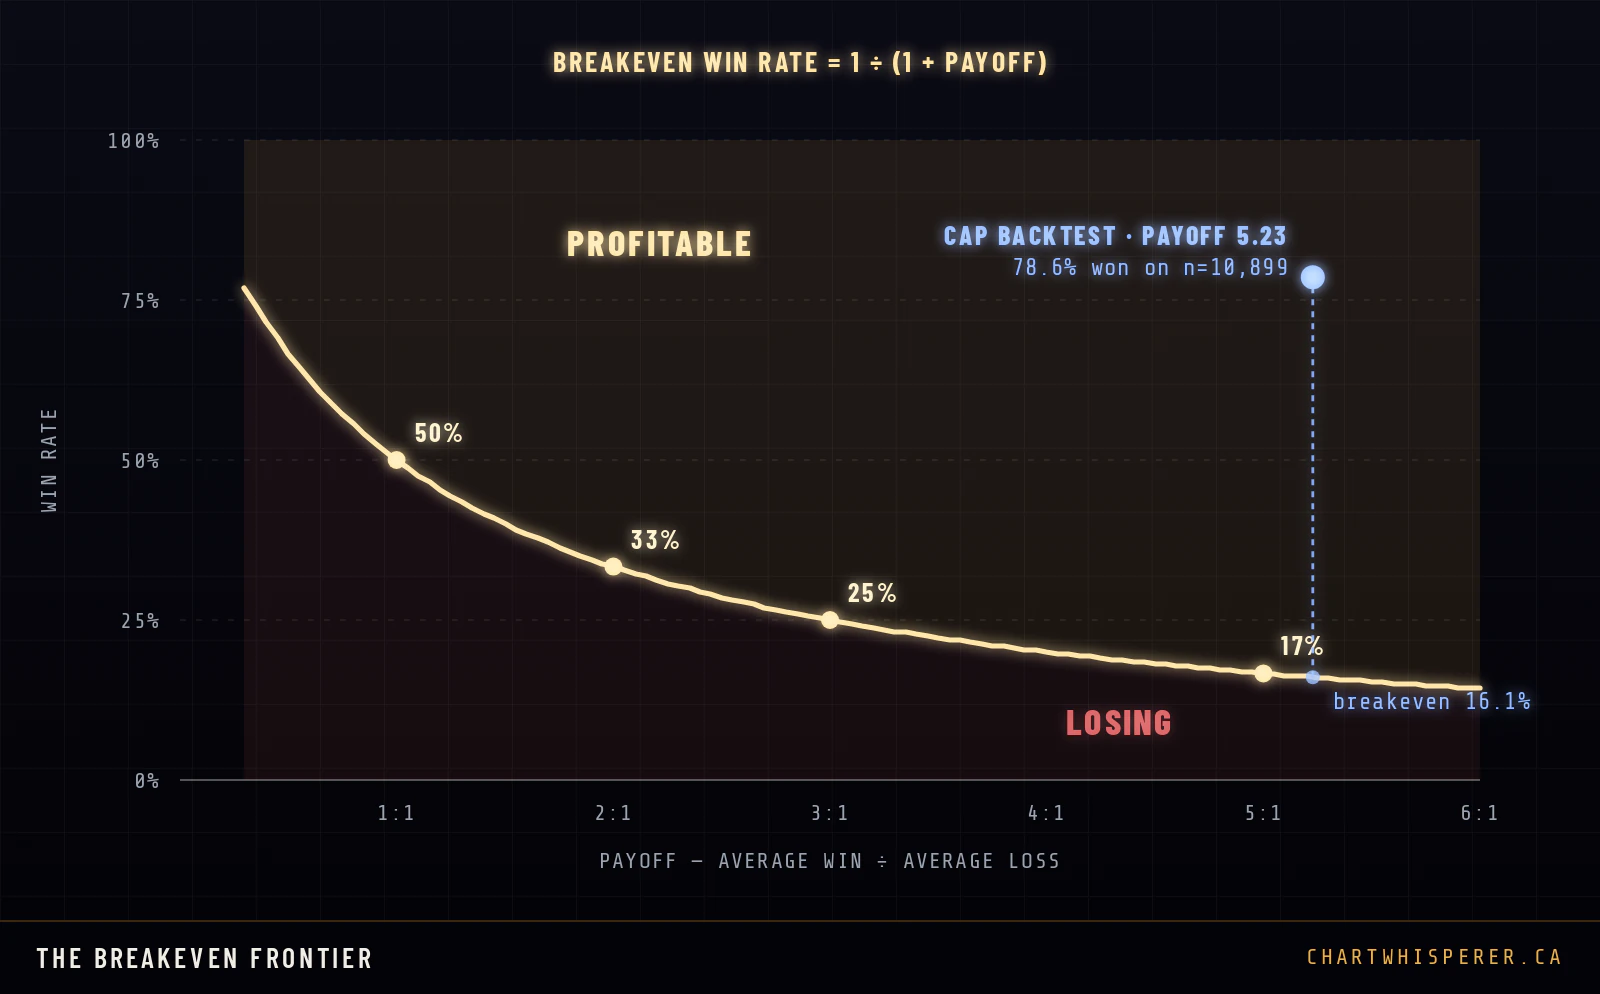
Every system lives somewhere on one curve. Pick how much your average win pays relative to your average loss, and the curve tells you the minimum win rate that system needs just to stand still. Above it you make money. Below it you do not, however good the chart work.
Breakeven win rate = 1 ÷ (1 + payoff) · payoff = average win ÷ average loss
At 1:1 you must win half your trades. At 2:1 you need a third. At 3:1 you need one in four, and at 5:1 about one in six. That is why so much trading education chases asymmetry, and it is a good reason. It is not the only way to sit above the line.
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
| Payoff (avg win ÷ avg loss) | Breakeven win rate | What a losing streak feels like |
|---|---|---|
| 0.5 : 1 | 66.7% | Rare, but each loss erases two wins |
| 0.8 : 1 | 55.6% | Occasional, and a loss outweighs a win |
| 1 : 1 | 50.0% | A coin that must land your way |
| 2 : 1 | 33.3% | Two losses paid back by one win |
| 3 : 1 | 25.0% | Long runs of small losses are normal |
| 5 : 1 | 16.7% | Most weeks lose, a few pay for everything |
| 5.23 : 1 (the CAP backtest) | 16.1% | Short runs: the longest was 4 to 9 losses in a row, one position at a time (backtest, n=10,899) |
The trap hiding in this chart is behavioural, and it is the most expensive habit in trading. Taking quick small profits while letting losers run drags the average win down and the average loss up at the same time. That slides a system to the left and down, across the curve, without a single rule changing. It is why the disposition effect belongs in a money management guide.
THE 1% RULE
RISK SMALL, SURVIVE ANYTHING
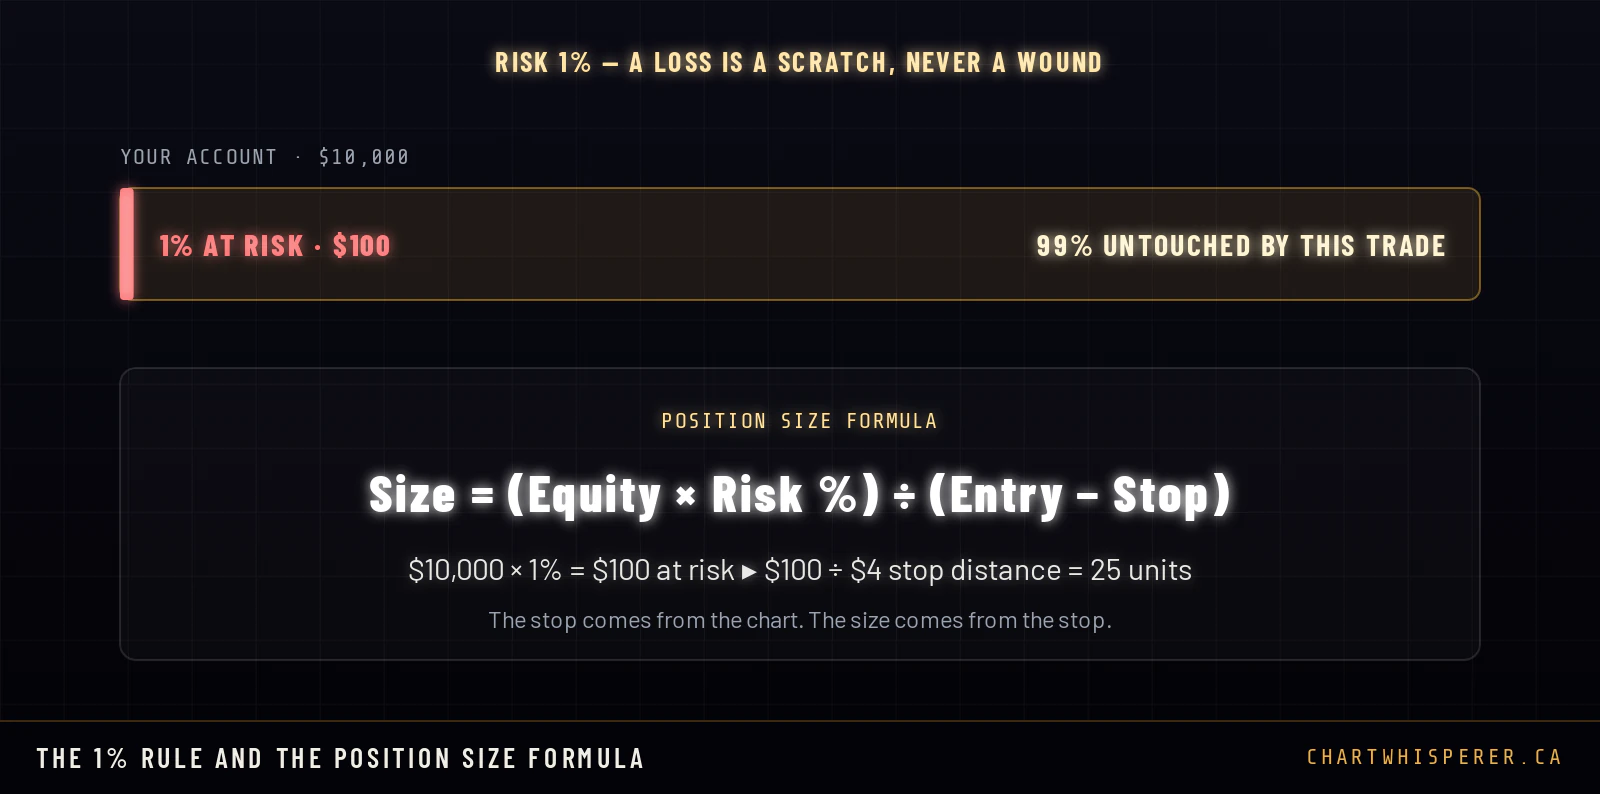
In plain EnglishNever let one trade cost you more than a small, fixed slice of your account. At 1%, a $10,000 account can lose at most $100 on any single trade.
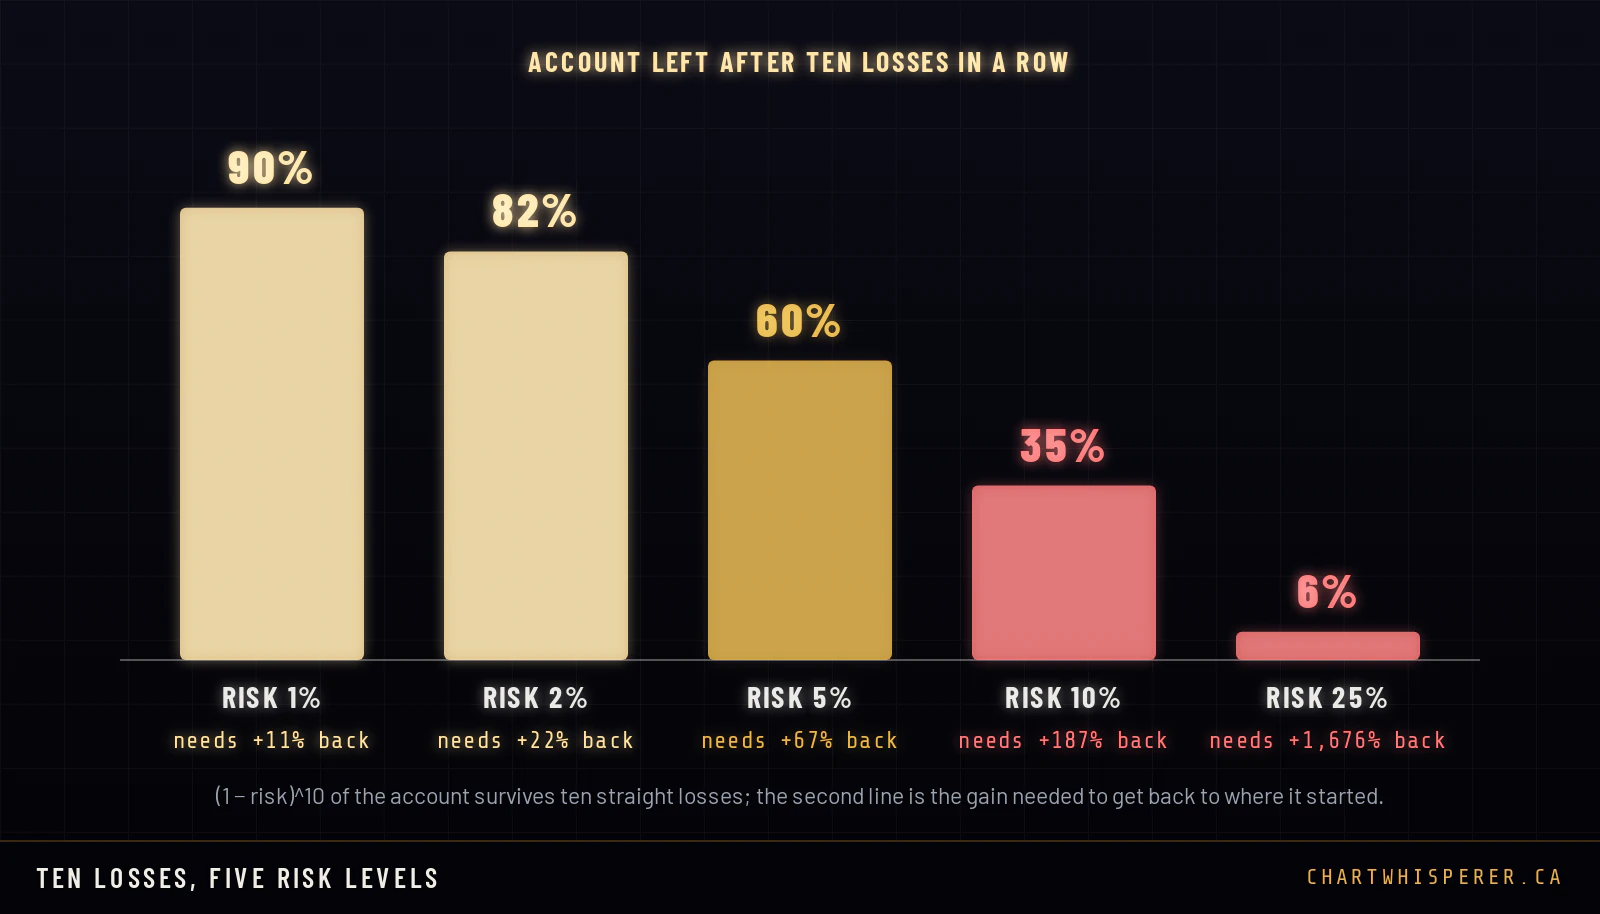
The single most important number in trading is not your win rate or your target. It is the slice of the account you allow one trade to take. Risk 1% and ten losses in a row cost about 10%, annoying and fully recoverable. Risk 20% and three losses cost you half the account. Same streak. Opposite outcome.
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
Most professionals use somewhere between 0.5% and 2% per trade, and the right number for you depends on three things you can measure: your win rate, your average loss in R, and the deepest drawdown you can sit through without changing your rules. The chapters below give you the tools to measure all three. Until you have them, 1% is a sensible ceiling, and 0.5% is not timid. It is how people survive the stage of their career where they do not yet know their own numbers.
One percent of what matters too. Fixed-fractional sizing uses current equity, so the dollar risk shrinks after losses and grows after wins. That is the version to use. It is a built-in brake: the deeper the drawdown, the smaller the bets, which is the opposite of what an emotional trader does.
On a small account the dollar amounts get tiny, and that is fine. Learning to size correctly on $1,000 is exactly the habit that protects $100,000 later. The guide to how much money you need to start covers the practical side, including why fees punish very small positions.
POSITION SIZING
THE STOP DECIDES THE SIZE
In plain EnglishFirst decide the price where you would be proven wrong. That is your stop. Then buy only as much as makes a loss at that price equal to your fixed risk. The calculator below does the math for you.
A wide stop means a small position. A tight stop means a large one. The dollars at risk never change. That is the entire discipline, and it is why a structural stop and a fixed risk fraction are two halves of the same rule.
Units = (equity × risk %) ÷ |entry − stop| · Notional = units × entry
Worked on a BTC perpetual. Account $10,000, risk 1%, so $100 is the most this trade may take. The CHoCH close gives an entry at 64,000 and the structural stop sits just beyond the last 4-hour swing at 63,360, a distance of 640, which is exactly 1%. Units = 100 ÷ 640 = 0.15625 BTC. Notional = 0.15625 × 64,000 = $10,000. If the stop is hit, 0.15625 × 640 = $100 is lost, plus costs.
Now tighten the zone. Same account, same entry, but the stop is 0.5% away at 63,680. Units double to 0.3125 BTC and the notional doubles to $20,000. Still $100 at risk. Widen it to 2% and the position halves to $5,000. Still $100.
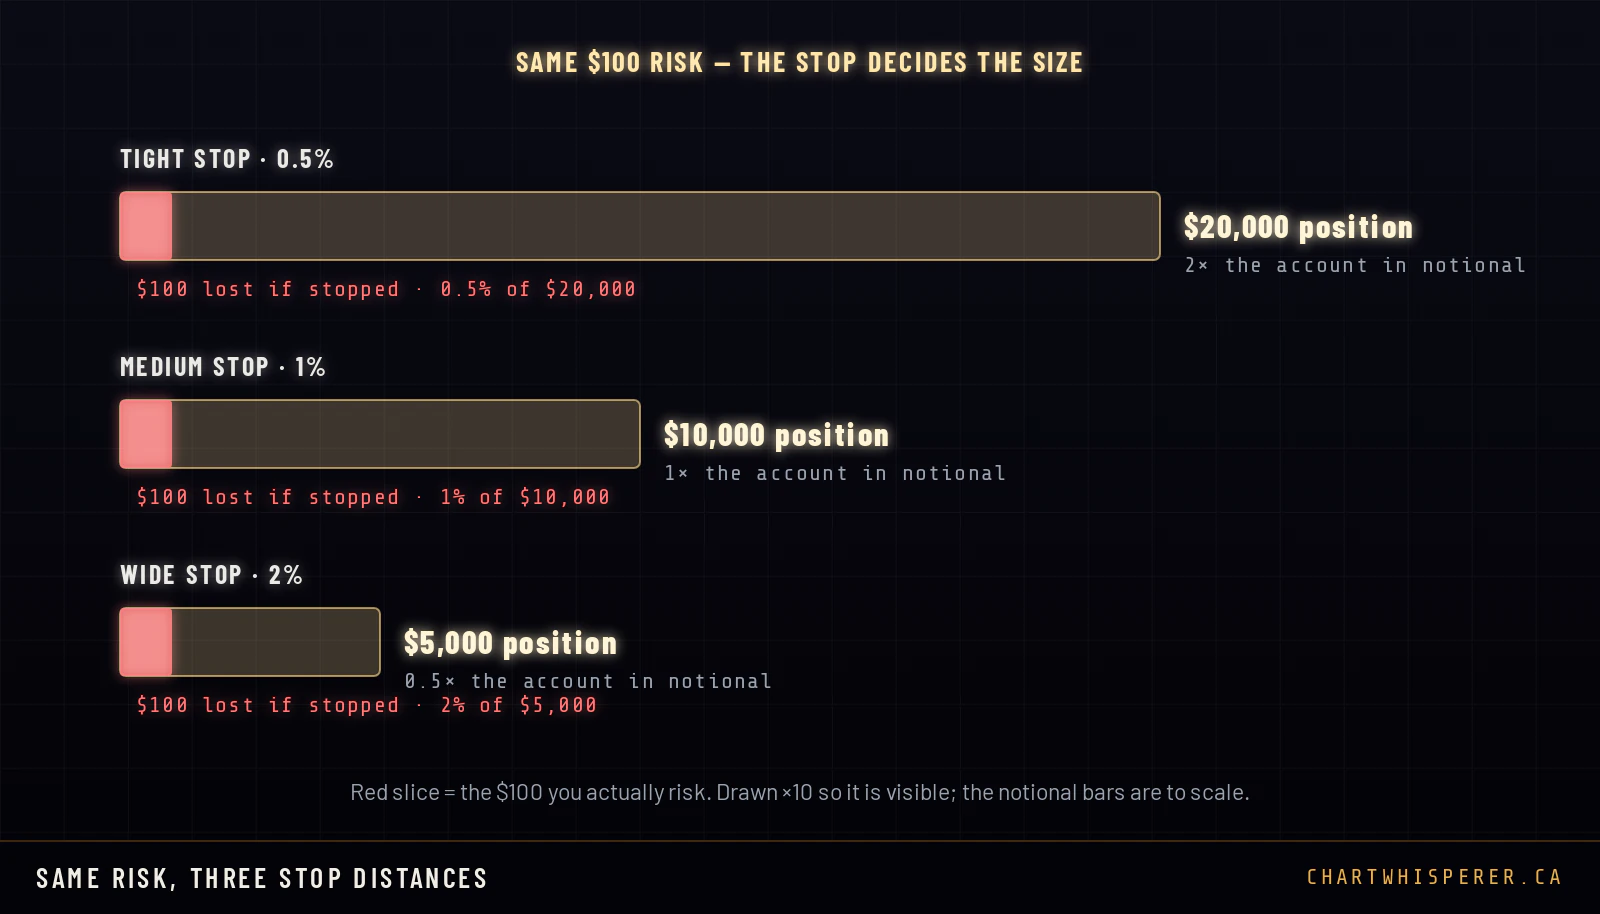
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
| Sizing model | How it sets size | Where it earns its place | Where it fails |
|---|---|---|---|
| Fixed fractional | A fixed % of current equity ÷ stop distance | The default. Shrinks bets in a drawdown, grows them at new highs. | Needs a structural stop to divide by. |
| Fixed dollar | The same $ risk on every trade | Simple for a new account or a prop challenge with a fixed limit. | Does not brake in a drawdown. |
| Volatility (ATR) | Stop set at a multiple of ATR, size solved from it | Keeps risk honest when the regime gets faster or slower. | An ATR stop is not a structural stop. Use it to sanity-check one. |
| Tiered by grade | Higher-graded setups take more of the allowed risk | A graded engine like CAP's confluence tiers. | Only if the tiers are measured, not felt. |
| Fixed units | The same number of coins every time | Nowhere. | Risk swings with every stop. It is not a sizing model. |
Liquidation sits beyond the stop. The stop fills first.
Liquidation estimated for isolated margin with a 0.5% maintenance rate; your exchange's tiers set the real price. A sizing tool, not advice on what to trade.
LEVERAGE IS NOT RISK
IT IS MARGIN, AND A LIQUIDATION PRICE
In plain EnglishLeverage lets you open a bigger position with less of your own money down. It does not change what you lose if your stop is hit, but too much of it lets the exchange close you out before your stop is ever reached.
This is the misunderstanding that ends more crypto accounts than any other. Leverage does not decide how much you lose. Your stop and your size do. Leverage only decides how much of your account the exchange holds as collateral, and how close the liquidation price sits to your entry.
Take the $10,000 position from the worked example. At 5× the exchange asks for $2,000 of margin. At 20× it asks for $500. At 50×, $200. The loss if the stop at −1% fills is $100 in every case, because the position is the same $10,000. What changes is the distance to liquidation, and that is where leverage bites.
Liquidation is the exchange closing the position because the margin behind it is nearly gone, and clusters of those prices are what a liquidation heatmap draws. For an isolated long it sits roughly at entry × (1 − 1 ÷ leverage + maintenance margin rate). Pile on enough leverage and that price climbs above your stop. The market never reaches your stop. It reaches your liquidation first, and you lose the full margin plus a liquidation fee instead of the planned 1%.
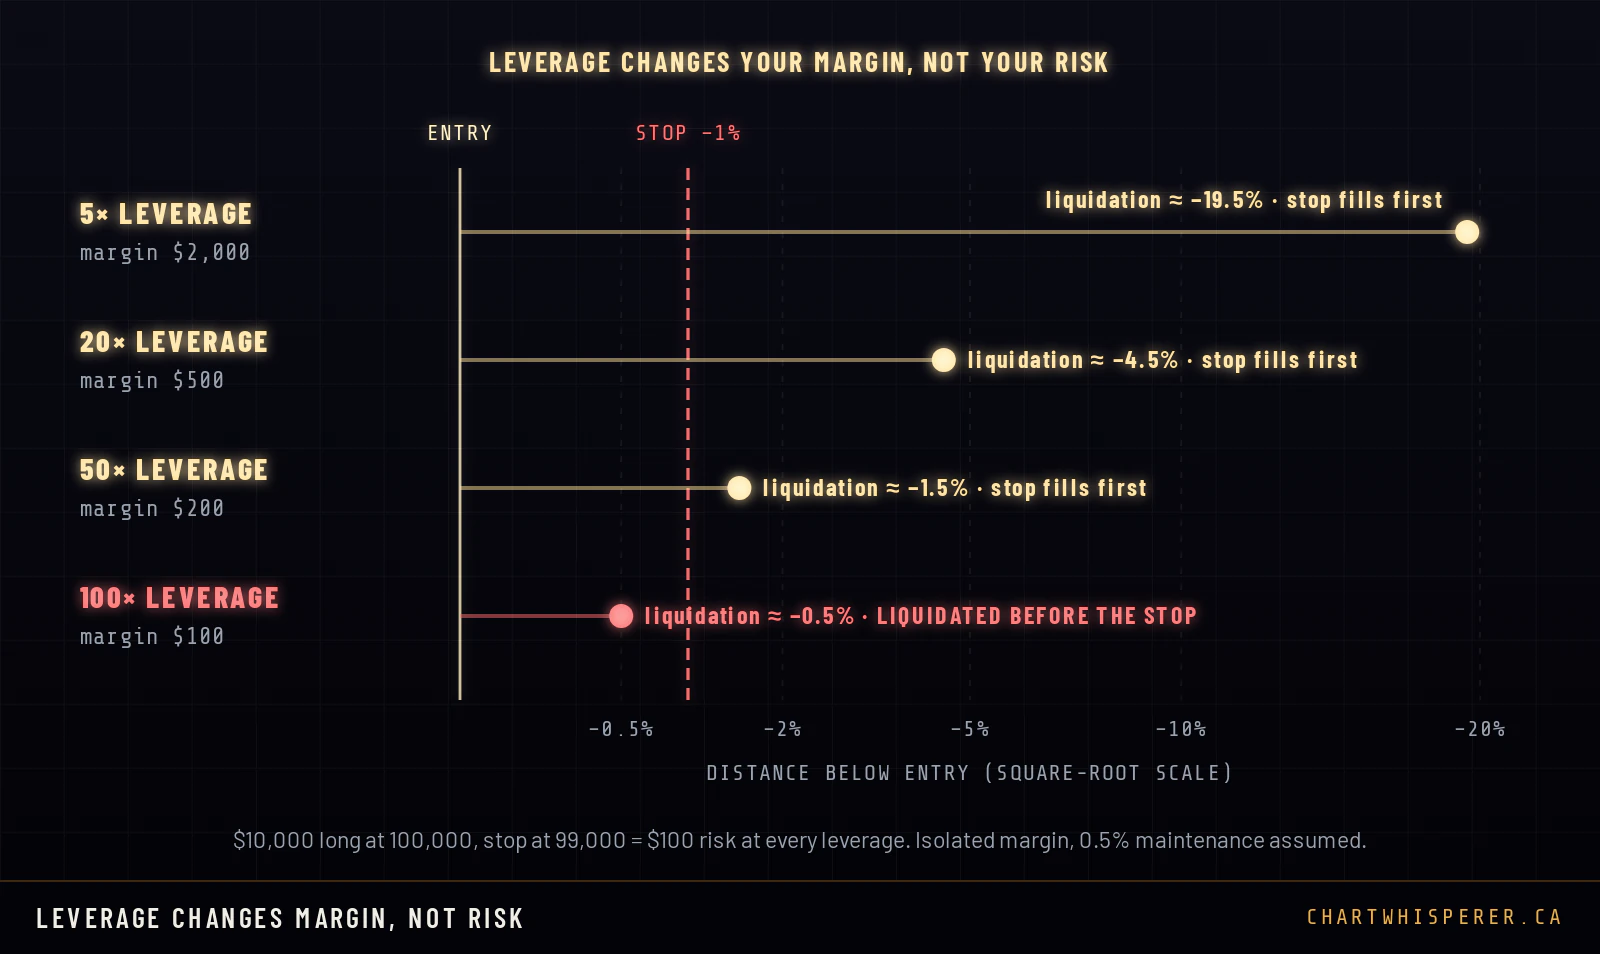
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
IF the stop is set and the size is solved
THEN choose leverage only so the margin fits, and confirm liquidation sits well beyond the stop
IF the exchange shows a liquidation price closer than your stop
THEN cut the leverage, not the stop. Never move a structural stop to fit a margin number
IF you run several positions on cross margin
THEN remember one position's loss eats the margin behind all of them. Isolated margin keeps each trade's damage to its own collateral
IF a trade is held across funding intervals
THEN price the funding as part of the trade's cost in R. It is charged on the notional, not on the margin
THE KELLY CRITERION
AND WHY NOBODY SANE BETS IT
In plain EnglishThere is a mathematically best bet size for growing an account, and in real life it is far too large. Professionals bet a small fraction of it.
In 1956 John Kelly, working at Bell Labs, published the formula for the bet size that grows a bankroll fastest over the long run. Edward Thorp took it to the blackjack tables and then to Wall Street. It is correct, it is beautiful, and almost every professional who uses it bets a fraction of what it says.
Kelly fraction = W − (1 − W) ÷ b · W = win probability, b = payoff ratio
For an illustrative system that wins half its trades and pays 2R per win against 1R per loss, Kelly says risk 25% of the account on every trade. Read that again. A quarter of the account on one trade, and it is the mathematically optimal number.
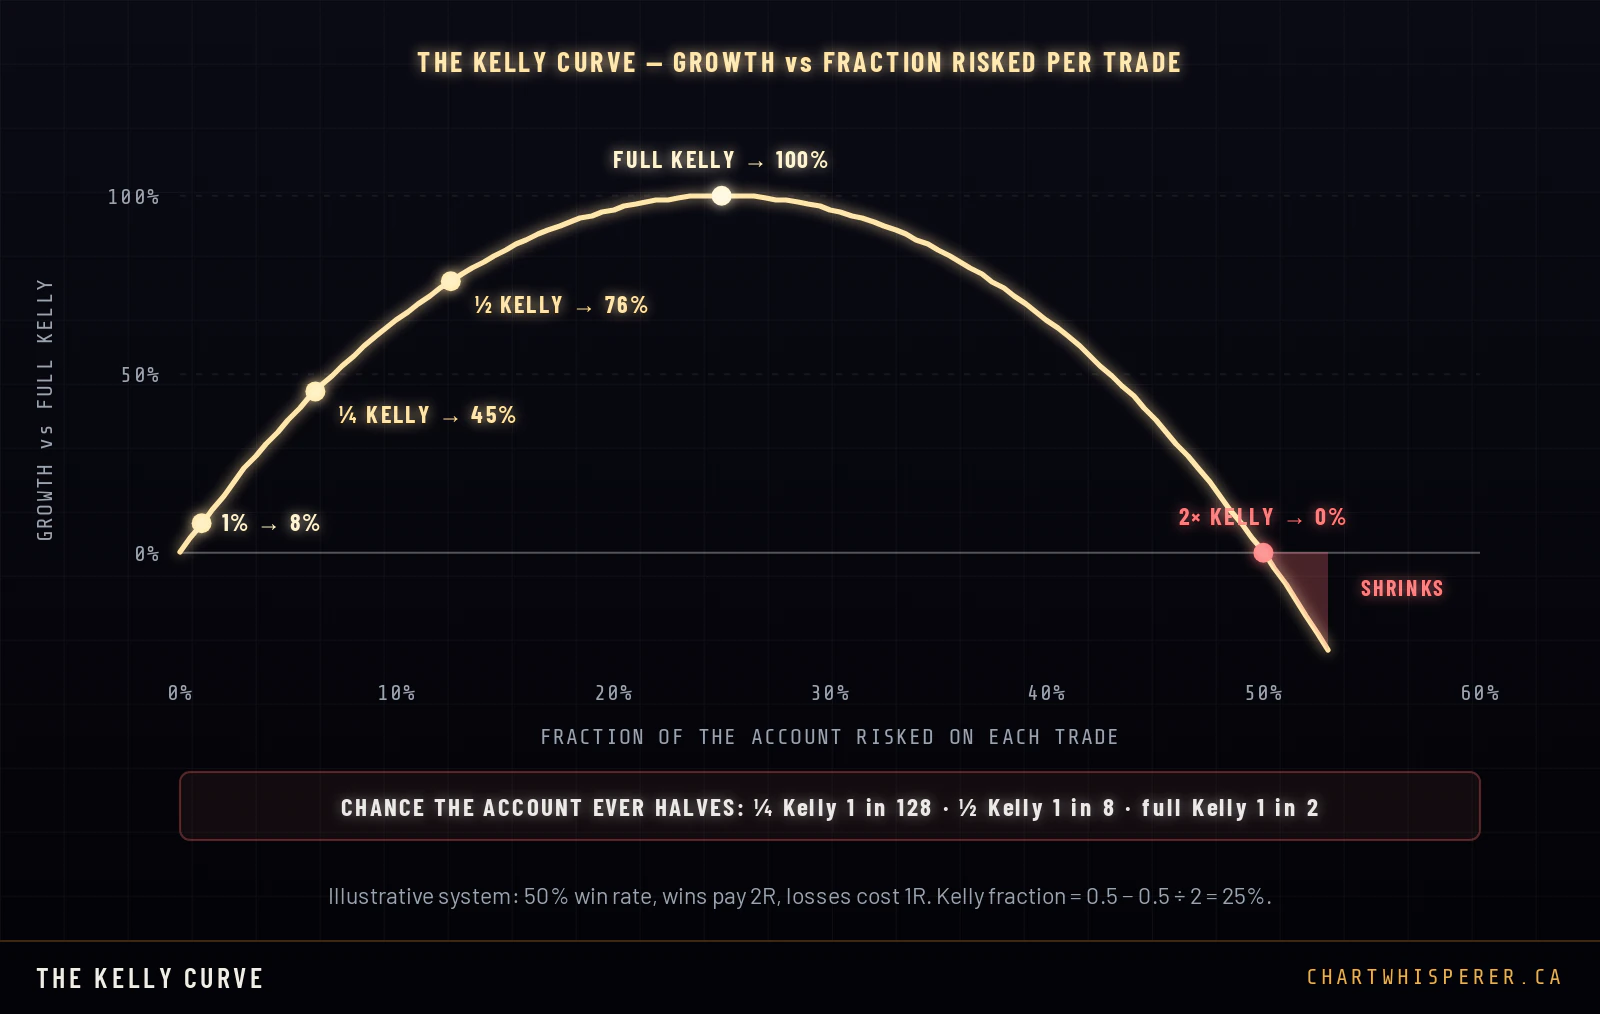
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
Three reasons nobody sane bets full Kelly. First, the drawdowns are savage. At full Kelly there is a one-in-two chance the account halves at some point. At half Kelly it is one in eight, at quarter Kelly one in 128. Second, you never know your edge exactly. Kelly assumes the true win rate and payoff. You have an estimate with a confidence interval, and overestimating the edge pushes you to the right of the peak, where growth collapses. Third, trades are not independent coin flips. Correlated positions, regime changes and fat-tailed losses all make the real curve harsher than the textbook one.
So treat Kelly as a ceiling you should never touch, not a target. It does something useful even so. It proves that there is such a thing as betting too much on a genuine edge, and that the penalty for it is not a smaller profit but a smaller account. The 1% rule sits far to the left of the peak on purpose. You give up some theoretical growth and buy an account that survives your own estimation errors.
LOSING STREAKS
ARE A CERTAINTY, NOT A SIGNAL
In plain EnglishEven a good strategy loses several trades in a row. That is ordinary chance, not a sign the strategy has stopped working.
A losing streak feels like information. It feels like the market has changed, the edge has broken, the rules have stopped working. Most of the time it is none of those. It is what randomness looks like when you finally take enough trades to see it.
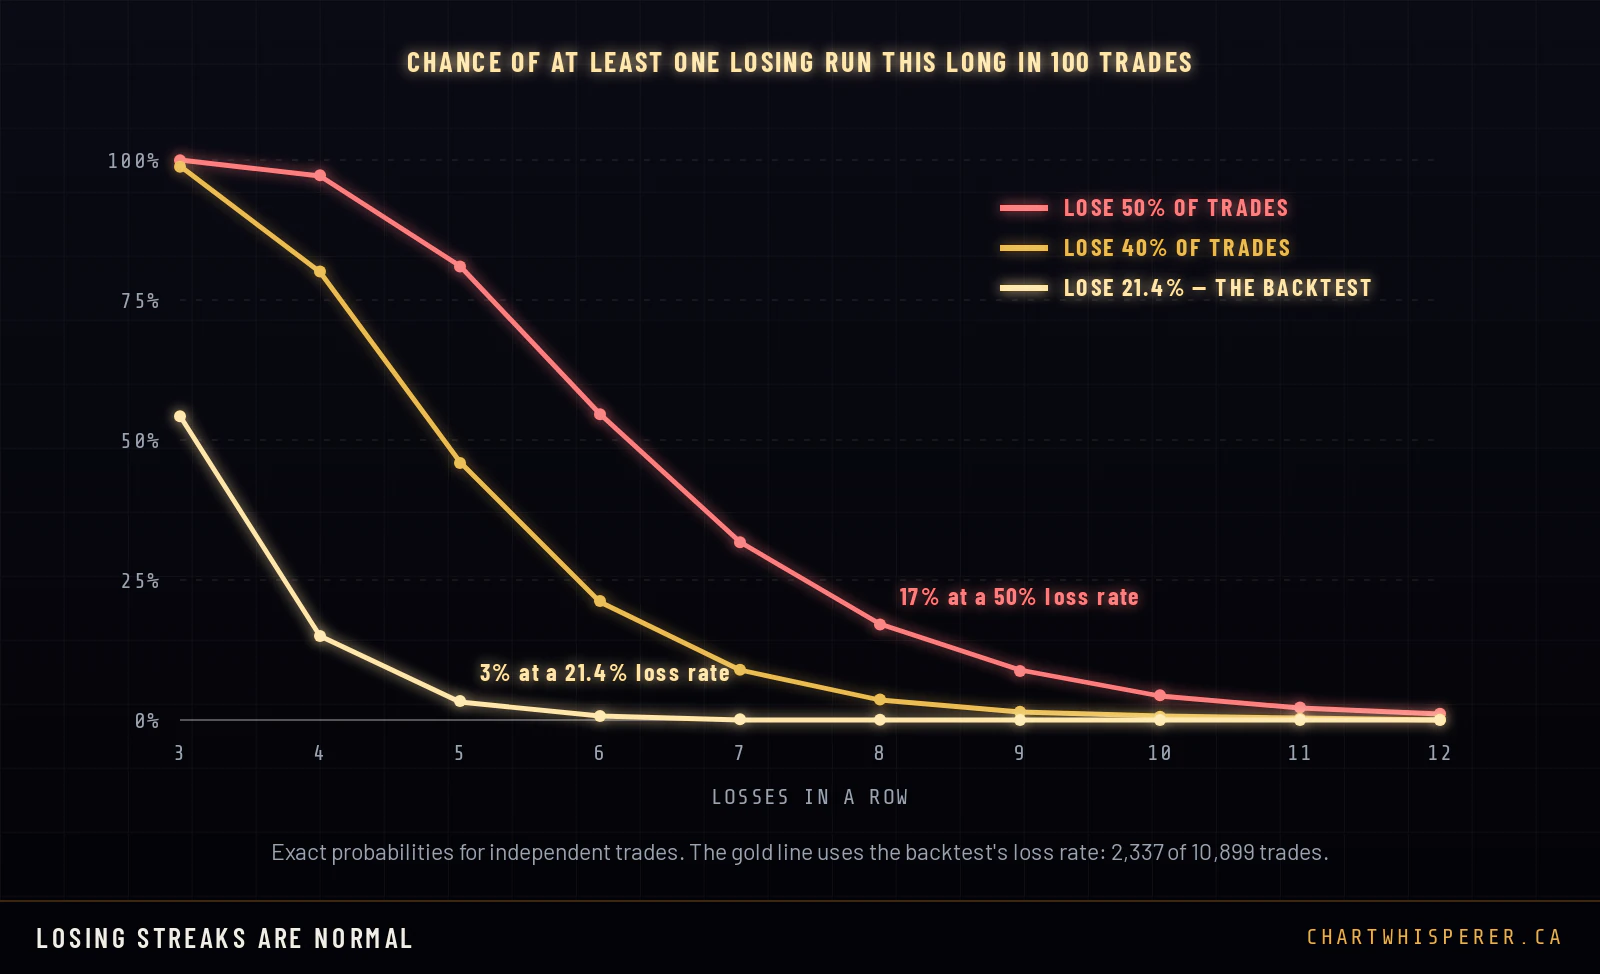
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
Here is the part that should change how you feel about your own streaks. The backtest loses only 21.4% of its trades, so the coin-flip arithmetic says a run of five losses in 100 trades should be rare, about 3%. Yet one position at a time, the worst version on Ethereum lost eight in a row and the worst on Solana nine. If trades were independent, a nine-run on Solana’s sample would be well under a 1-in-100 event. Real losses cluster. A bad stretch of market produces several losers together, so the streak you plan for has to be longer than the arithmetic alone suggests.
Two things follow. First, size for the streak you have not seen yet, not the one you have. If your own history shows a worst run of five, the next few hundred trades can easily show eight. Second, decide in advance what a streak is allowed to mean. A run inside the range the math predicts is noise and gets traded through at normal size. A run well outside it, or a drawdown well past your worst on record, is a reason to stop and review, and that decision is written down before it is needed.
RISK OF RUIN
THE SAME STREAK, FIVE FATES
In plain EnglishRisk too much per trade and an ordinary losing run can wipe out the account. Risk a little and the very same run is survivable.
Risk of ruin is the probability that a run of losses takes the account to a point it cannot come back from. It is not bad luck. It is a number you choose in advance, every time you decide how much to risk per trade.
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
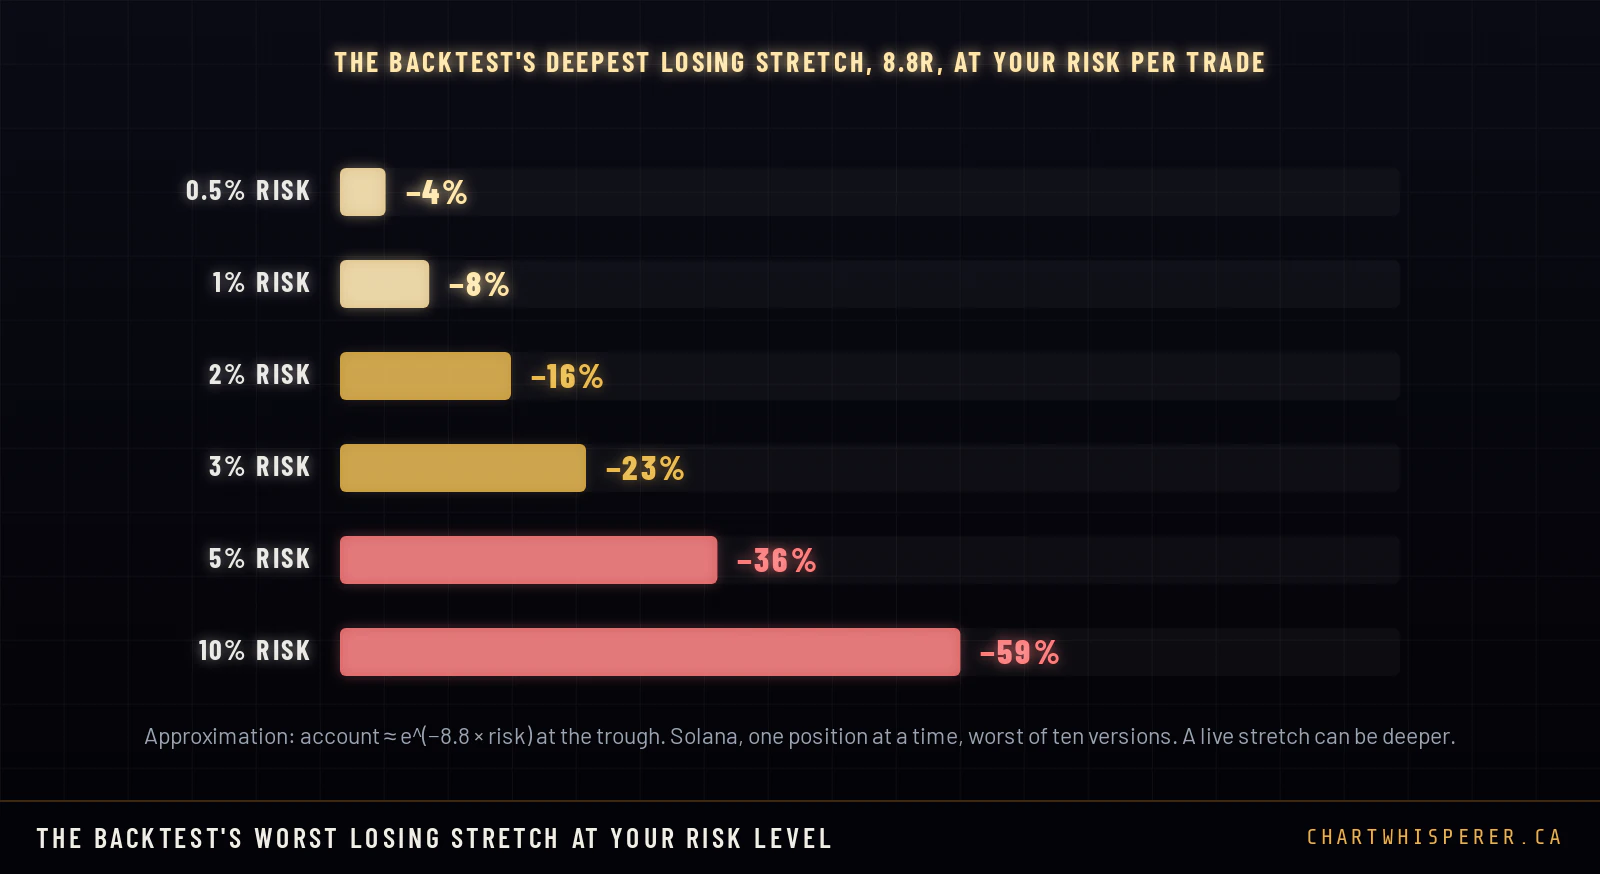
A streak of ten is a stress test, not a forecast. The more useful question is what a realistic worst case costs at your risk level, and the published backtest gives us one. Taking one position at a time, its deepest losing stretch was 8.8R, on Solana, in the worst of the ten versions. At 1% risk per trade that is roughly an 8% fall in the account. At 2% it is about 16%. At 5% it is about 36%, a hole that needs a gain of roughly 55% just to get back to where it started.
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
THE DRAWDOWN TRAP
LOSSES AND GAINS AREN’T EQUAL
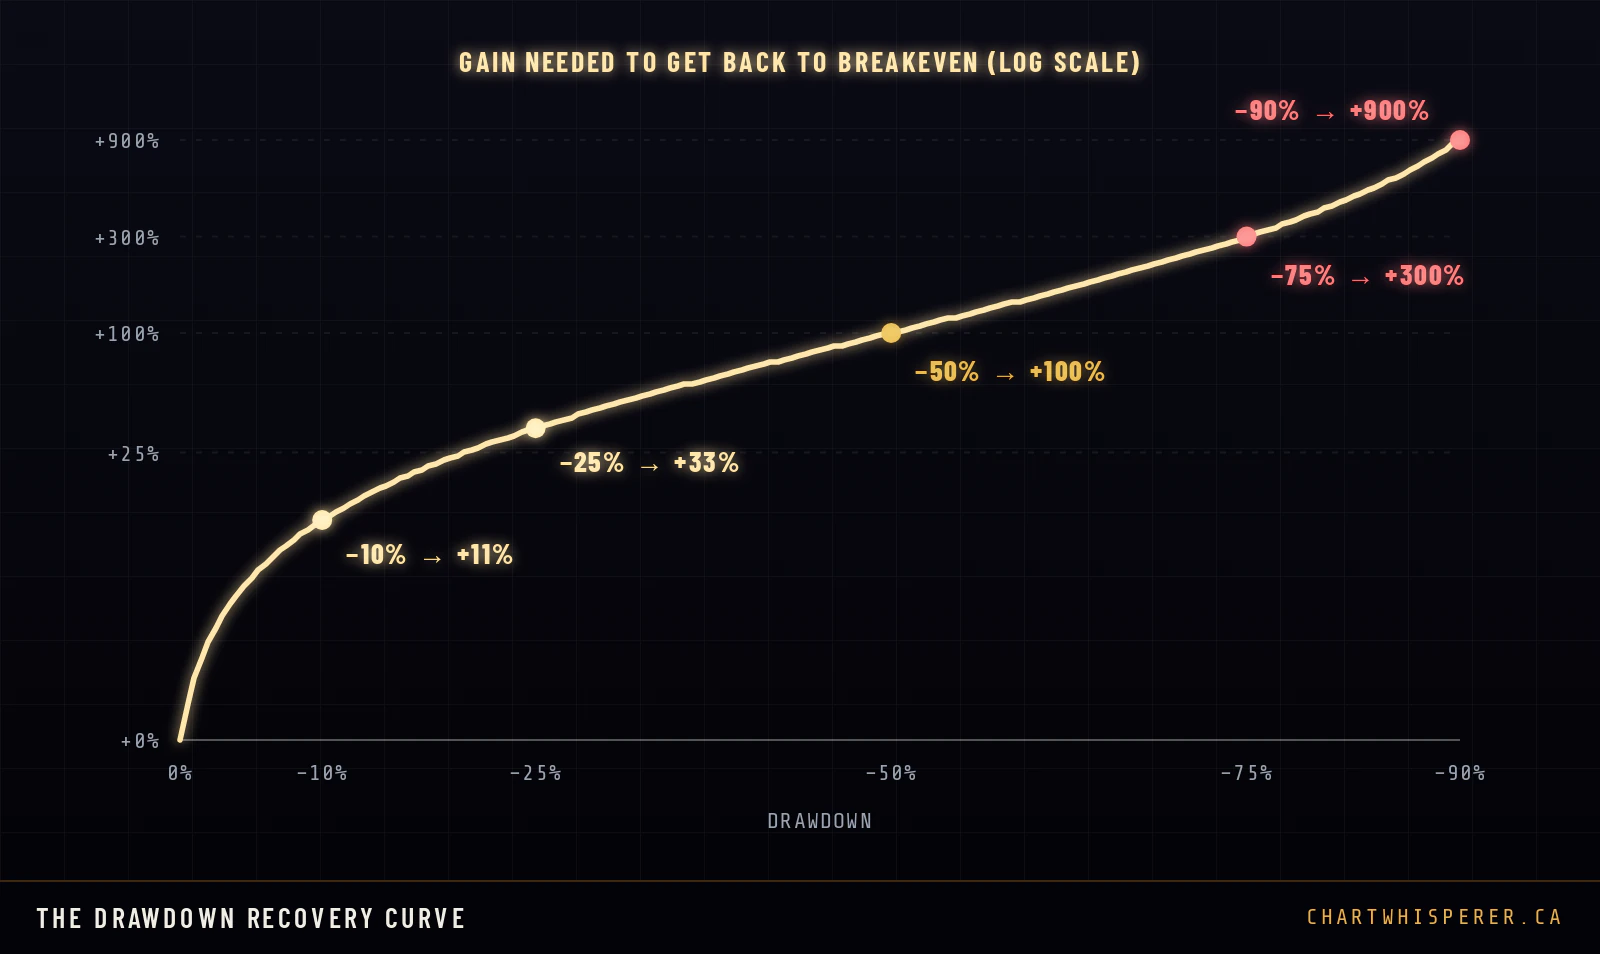
In plain EnglishMoney is easier to lose than to win back. Lose half the account and you have to double what is left just to get back to where you started.
A loss and the gain needed to undo it are not the same size. Lose 10% and you need +11% to get back. Lose 50% and you need +100%, because you have to double what is left. Lose 75% and you need +300%. The hole deepens faster than the loss, because every recovery compounds off a smaller base.
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
There is a second, quieter cost that the curve does not show. Time. Even at the backtest’s stress-tested average of about +2R a trade, a 9R hole takes four or five average trades to refill, and at roughly ten trades a coin a year that is months, and averages are not guaranteed. A trader who risks enough to fall 50% is not just facing a +100% climb. They are facing months of trading at reduced size, under pressure, which is exactly the state in which rules get broken.
This is also why the most dangerous moment in a drawdown is the urge to size up to get back faster. It feels like a recovery plan. On this curve it is a move toward the steep end.
SAME EDGE
DIFFERENT PATHS
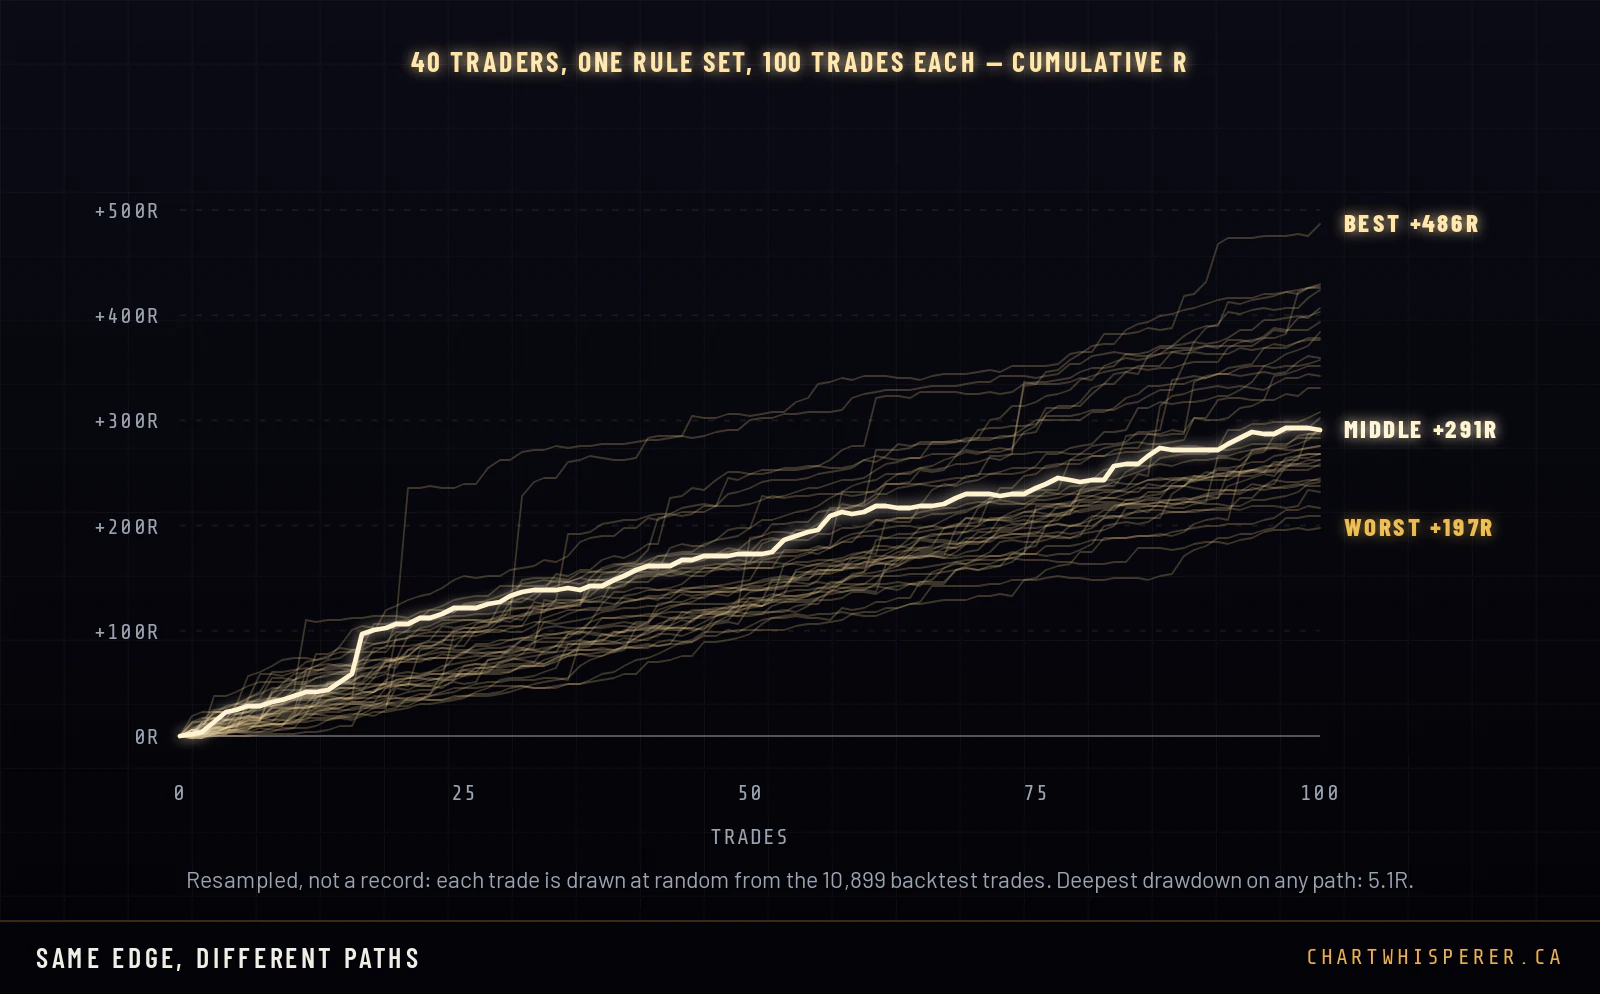
In plain EnglishForty people using the same strategy get forty different results. Luck decides a lot over a few hundred trades, and small risk is what lets you last until the strategy's real edge shows up.
Give forty traders the same edge and the same rules, and they will not get the same result. Over a few hundred trades luck decides a surprising amount of where each one ends up, and it decides even more about what the journey feels like.
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
Read it two ways. The comforting way first: every path finished well up, because a genuine edge sampled enough times tends to show up. Then the honest way. Even with identical trades, the luckiest path made more than twice what the unluckiest did, and these paths assume the future looks like 2018 to 2026 and that every trade is taken exactly. Real losing trades also come in clusters: one position at a time, the backtest’s worst Solana version lost nine in a row. If your first stretch looked like that, would you still be following the rules on the next trade? Most people would not. They would have changed the system three times by then.
That is the practical case for small size. It is not only about surviving the worst streak. It is about keeping the losses small enough that you can keep executing a real edge through a stretch of bad luck long enough for the edge to show. The psychology chapter on judging decisions rather than outcomes is the other half of the same idea.
PORTFOLIO HEAT
& CORRELATION
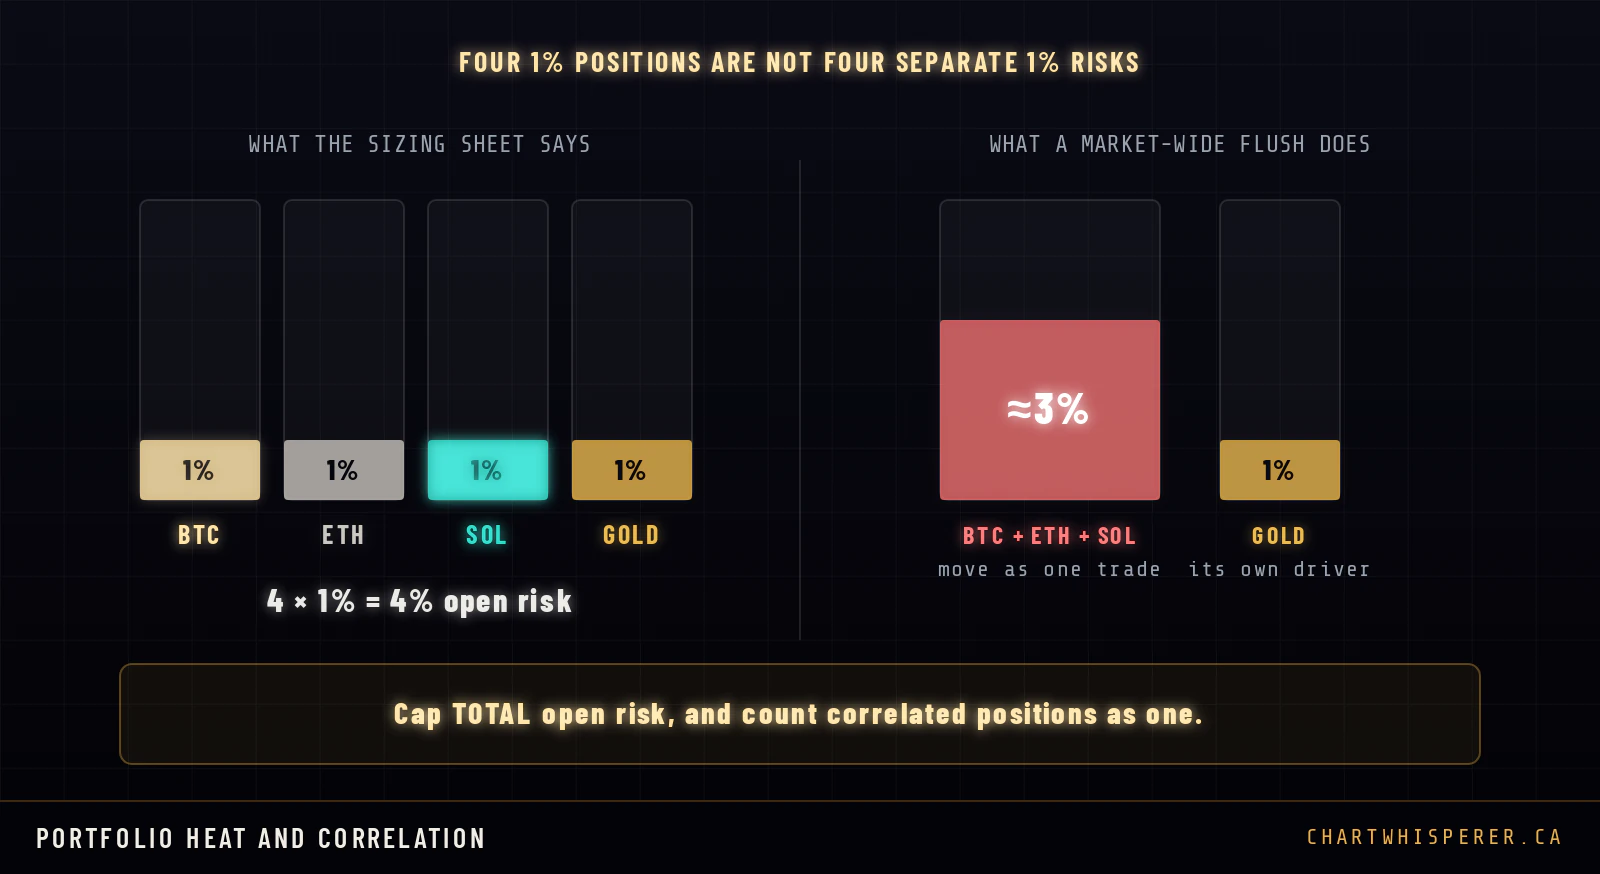
In plain EnglishSeveral trades in coins that tend to move together are really one bigger trade. Add up the total you have at risk across everything open, not just each trade on its own.
Per-trade risk is only half the job. The other half is how much is at risk across everything open at once, and how much of it will fail together. That total is called heat, and it is where careful traders get surprised.
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
The published backtest is a working example of the problem. It takes one position at a time on each coin, but the four coins run side by side, so at 1% risk per trade up to 4% of the account can be at risk at once on /protocol-results. That is a portfolio decision, and it is disclosed as one, because the per-trade figure alone would understate it.
Three rules keep heat under control. Cap total open risk at a number you have tested against your worst drawdown, not a number that sounds reasonable. Count positions in correlated assets, or in the same direction on the same idea, as a single position for that cap. And when a new setup would take you over the cap, the answer is no trade or a smaller one, never a stop moved closer to make the numbers fit.
CIRCUIT BREAKERS
DAILY LIMITS & DRAWDOWN TIERS
In plain EnglishDecide your rules for bad days before they happen: stop for the day after a set loss, and trade smaller while the account is below its high.
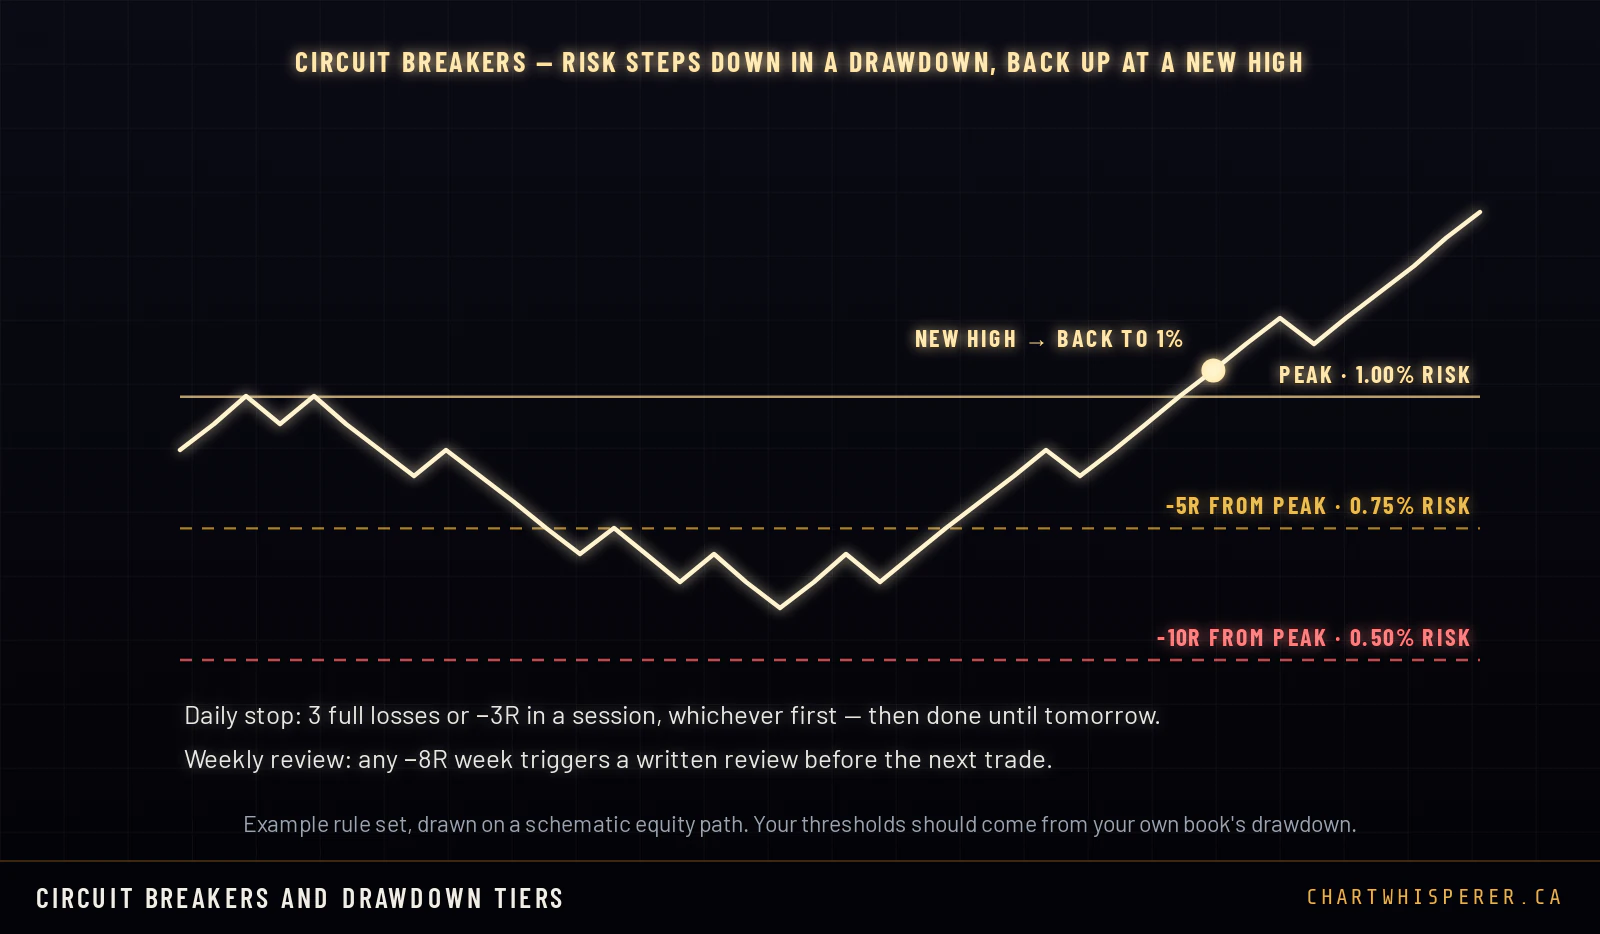
Every serious risk desk has hard stops that apply to the trader, not the trade. A daily loss limit. A drawdown level at which size is cut. A point at which trading stops and a review starts. They are written down in advance, because the moment they are needed is the moment you are least able to write them.
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
Prop firms enforce the first of these for you, and it is instructive how many traders fail on it. If a challenge has a 5% daily loss limit and you risk 1% per trade, five full losses in one session end the account. A three-trade daily cap makes the limit arithmetically unreachable: 3 × 1% plus costs is well inside 5%. That is the whole trick. You do not avoid the daily limit by trading better on a bad day. You make it impossible to reach before the first trade is placed.
IF three full losses have printed today, or the day is down 3R
THEN the session is over. No fourth trade, whatever the chart shows
IF equity is 5R below its last peak
THEN risk per trade steps down, for example from 1% to 0.75%, until a new high
IF equity is 10R below its last peak
THEN risk steps down again, and every trade is reviewed against the written rules before the next one
IF a drawdown runs well past the worst on record
THEN stop trading live. Review the sample, the regime and your execution before risking another R
MARTINGALE
vs ANTI-MARTINGALE
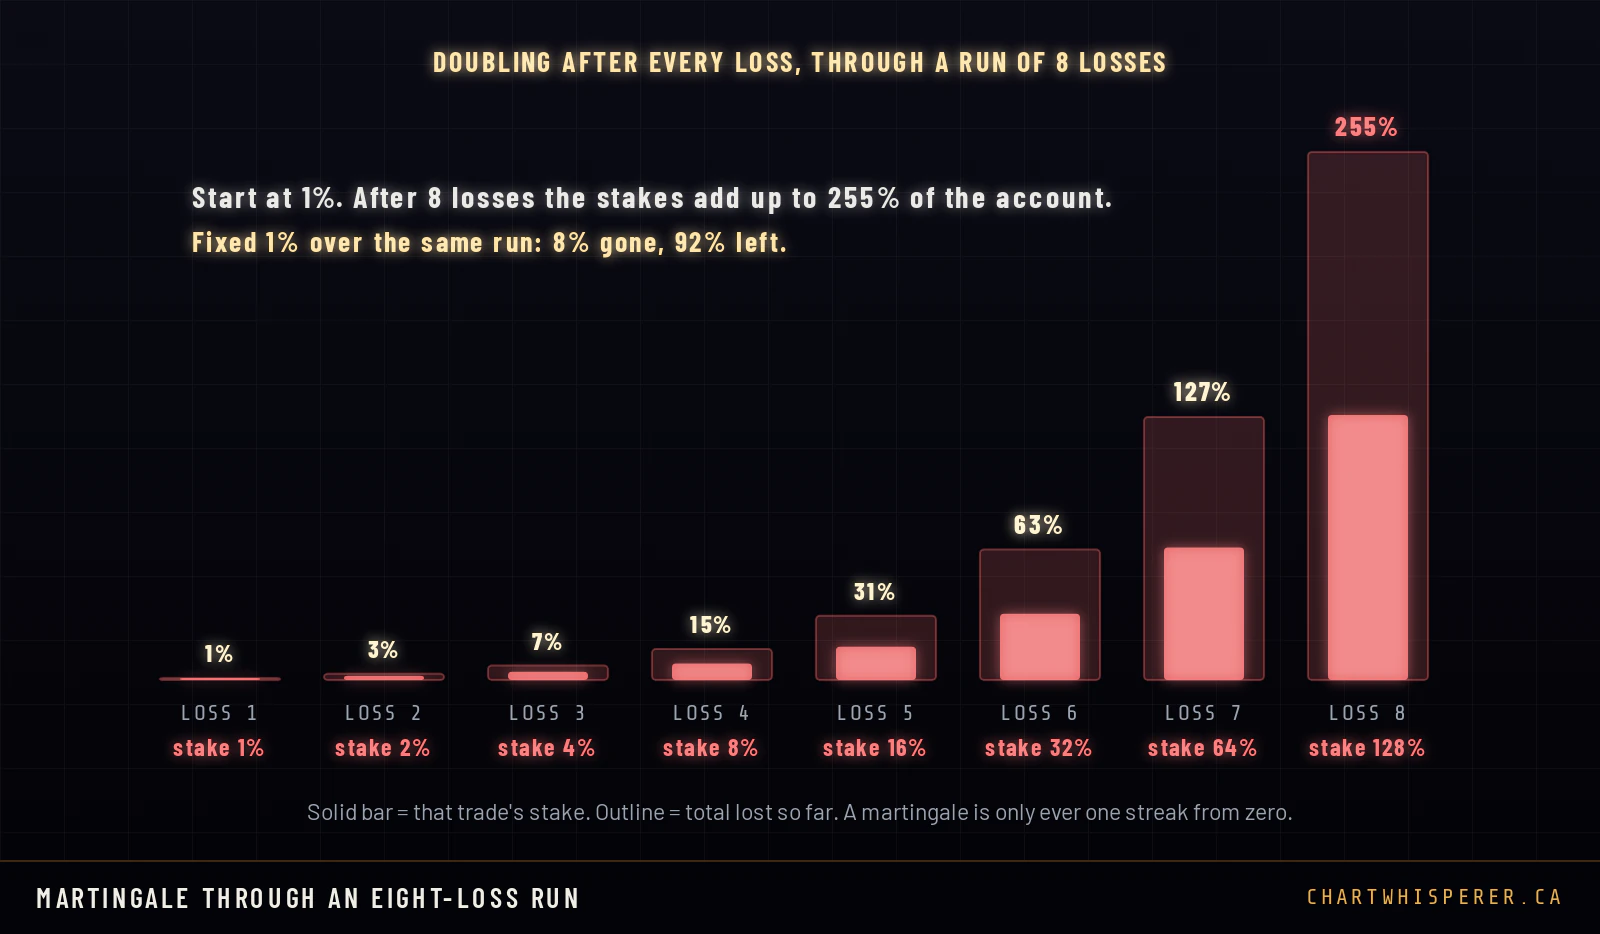
In plain EnglishDoubling your bet after a loss to win it back looks clever and ends accounts. After losses, keep your risk the same or make it smaller, never bigger.
A martingale doubles the bet after every loss, so that one win recovers everything plus the original stake. On paper it cannot lose. In practice it is how a long career ends in an afternoon, and averaging down into a losing position is the same idea wearing a suit.
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
Anti-martingale is the reverse and it is what fixed-fractional sizing already does. Size shrinks as equity falls and grows as it rises, so the account takes its biggest swings when it has the most room to absorb them. It is less exciting and it is the version that is still trading next year.
The same logic covers adding to a loser. The stop marked where the idea was wrong. Adding size between the entry and that stop raises the dollars at risk above the planned 1%, on the one trade that has already told you it is not working. If a setup deserves more size, it deserves it at entry, through a higher grade, never through a lower price.
COSTS ARE MEASURED IN R
AND TIGHT STOPS PAY THE MOST
In plain EnglishTrading fees look tiny as a percentage, but when your stop is close to your entry they eat a large share of what you risked on the trade.
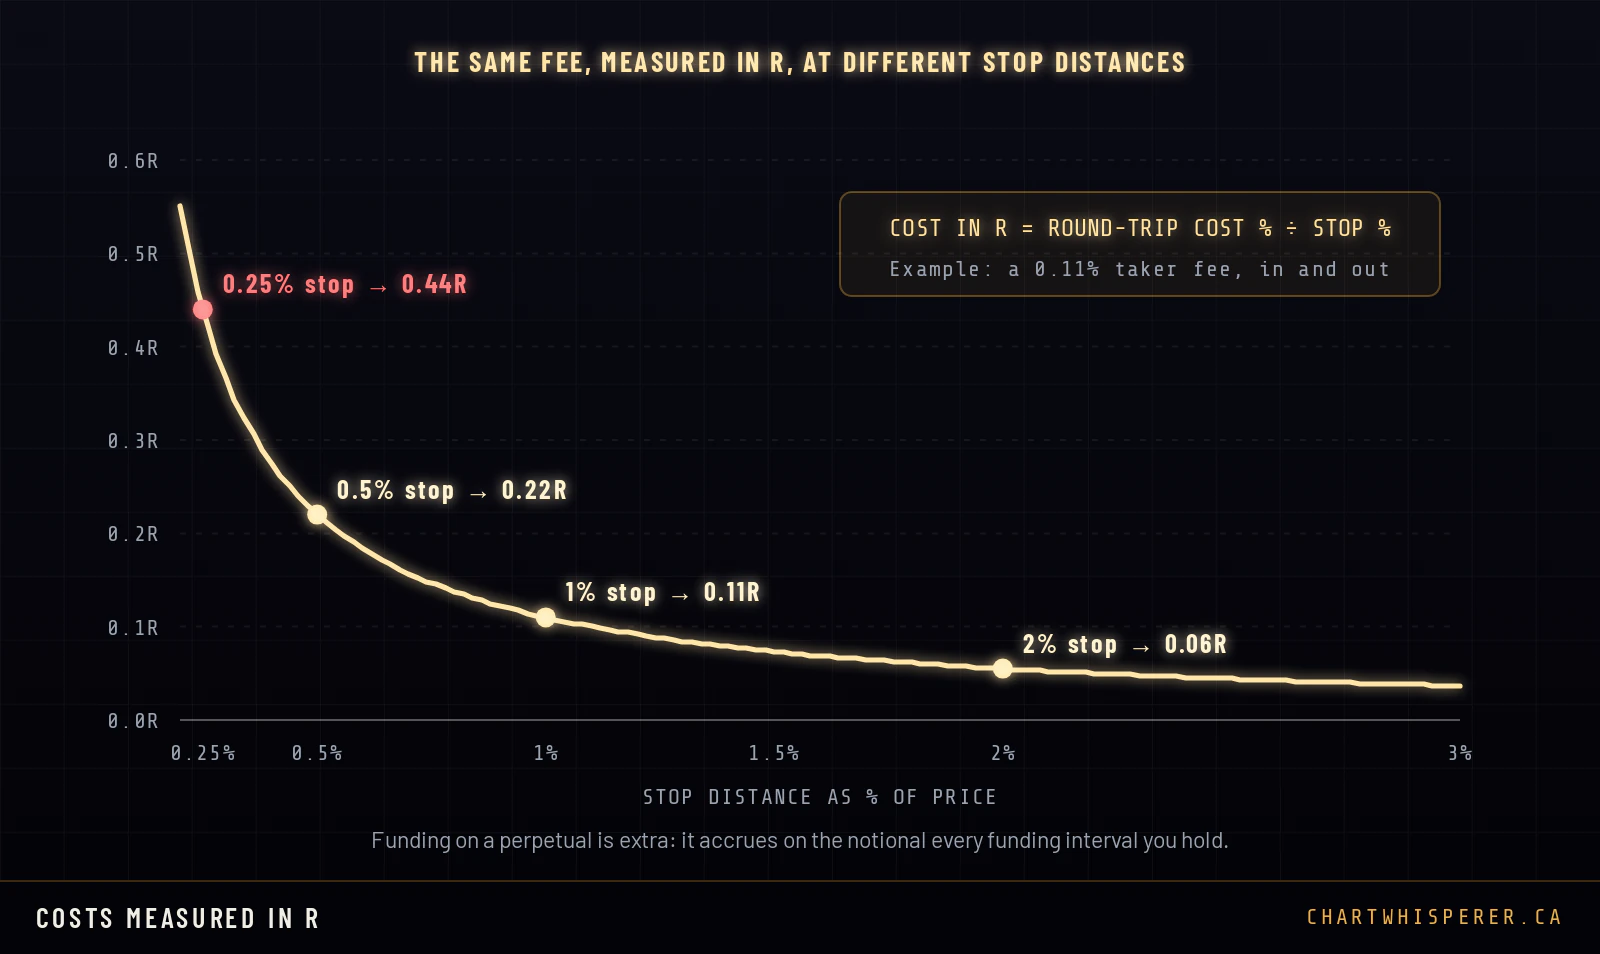
Fees are quoted as a percentage of what you trade. Your risk is quoted in R. Put the two in the same unit and something uncomfortable appears: the same fee costs four times as much R on a stop a quarter the size.
Cost in R = round-trip cost % ÷ stop distance %
Take an example taker fee of 0.11% for the trip in and out, and measure it against each trade's own stop distance. On a 1% stop that is 0.11R per trade. On a 0.5% stop, 0.22R. On a 0.25% stop, 0.44R, nearly half of the risk unit gone before price moves.
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
Two practical consequences. First, a strategy that looks brilliant before costs on very tight stops can be worthless after them, so always test net of fees in R, never gross. Second, on perpetuals, funding is an extra cost on the notional every funding interval you hold. A position held across several intervals at a positive rate pays it each time, and on a tight stop that adds up to a real slice of R. Price it into the plan the same way. The funding rates guide covers how it is set.
SCALING OUT
WHAT A LADDER REALLY PAYS
In plain EnglishTaking some profit early is sensible, but it means the average win ends up much smaller than the best-case target. Plan with the average, not the best case.
The tested CAP rules have no target ladder at all. The stop sits beyond the last 4-hour swing and the whole position is held until the bigger move ends. So the only honest summary is what actually happened to every trade.
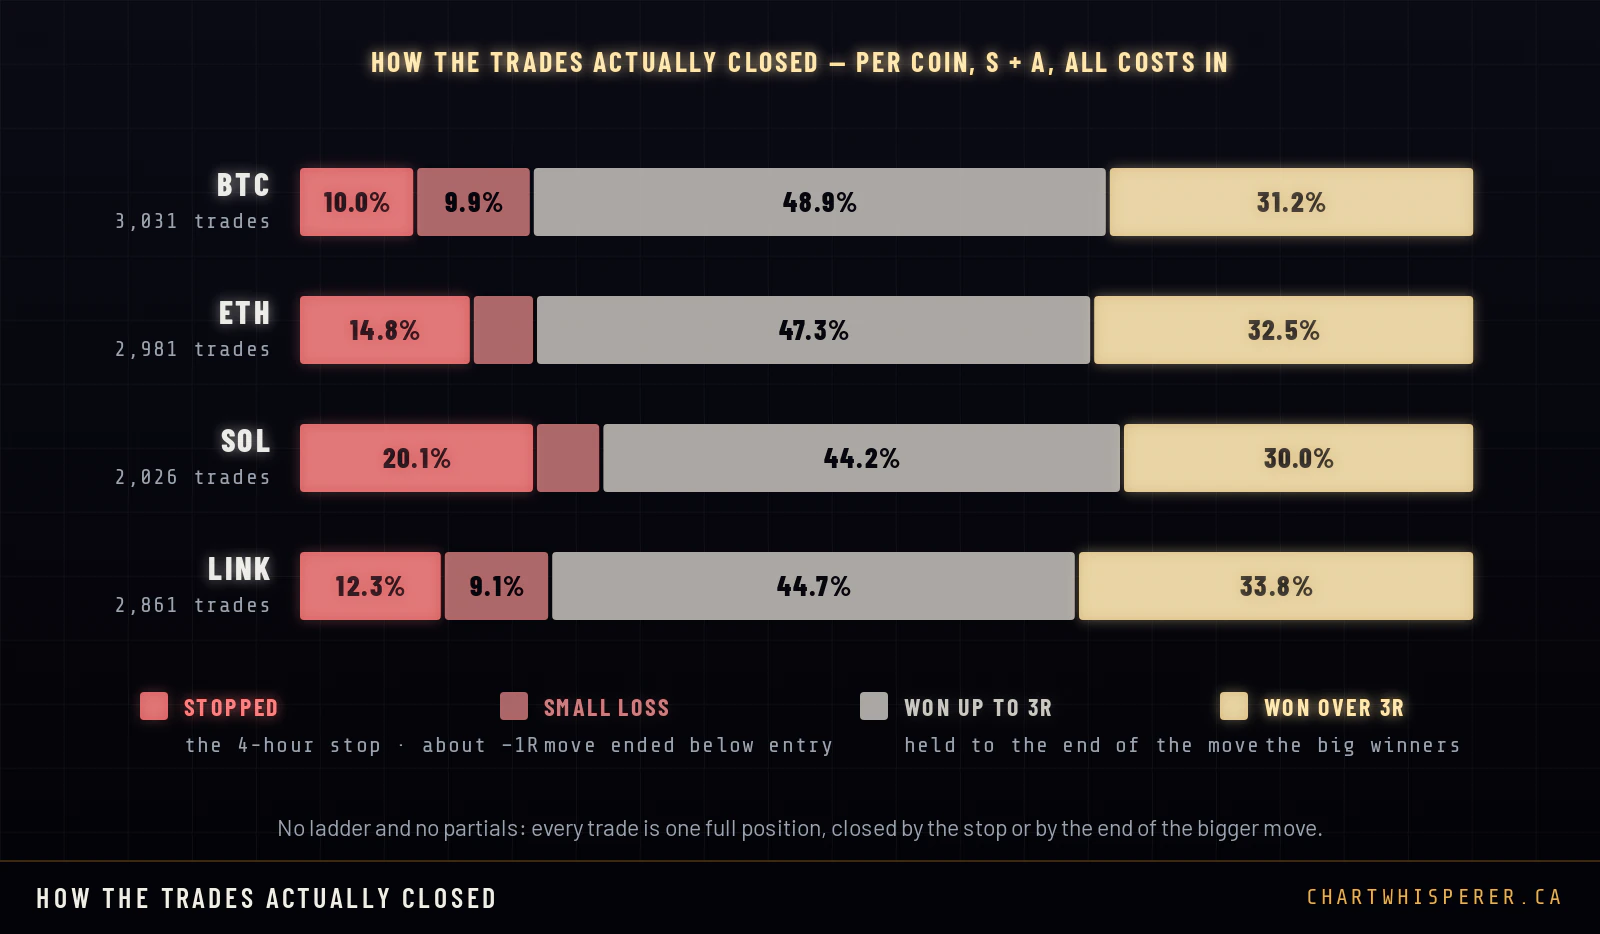
Press and hold the image (right-click on a computer) to save it. Free to reuse with credit: how to credit The Chart Whisperer.
This is the most common way trading results get misrepresented, including by honest people: quoting a target as if it were a result. A target describes where a trade could end. The exit mix describes what happened. This site publishes only the second, trade by trade, which is why every one of the 10,899 backtest trades can be downloaded and checked.
Scaling out has a real job in discretionary trading: banking part of a trade at a clear level reduces stress and can fund a re-entry. What it cannot do is change the arithmetic. The tested CAP rules hold the full position because, in the backtest, cutting winners early cost more than it saved. Whatever you choose, the expectancy is whatever your exit mix says it is, and you only learn that by logging every exit in R.
Your written
risk plan.
In plain EnglishWrite your risk rules on one page before you trade, then follow the page instead of your mood.
Everything above collapses into a single page you write once and follow every day. It is short on purpose. If it does not fit on a page, it will not survive a bad morning.
| Line in the plan | Example |
|---|---|
| Risk per trade | 1% of current equity, 0.5% until 100 trades are logged |
| Stop placement | Structural only: where the setup is invalidated. Never moved against the trade |
| Size formula | (Equity × risk %) ÷ |entry − stop|, costs added in R |
| Maximum open risk | 3% total, correlated positions counted as one |
| Daily stop | 3 full losses or −3R, then done for the day |
| Drawdown tiers | −5R from peak: 0.75%. −10R: 0.5%. Back to 1% at a new high |
| Review trigger | Any drawdown past the worst on record, or any rule broken twice in a week |
| Leverage | Only what the margin needs, liquidation well beyond the stop |
The numbers in that example are sensible starting points, not a prescription. The point is that every line is decided before the trade and none of them can be changed during it. Change them on a weekend, after reviewing the data, and never in the middle of a session.
The trading plan guide puts this page inside the full plan: markets, schedule, setups and review.
This is also the page you read after a loss. Not to feel better. To check one thing: was the rule followed. If it was, the loss was a cost of doing business and it goes in the log. If it was not, that is the only thing worth fixing, and it has nothing to do with the chart.
Every CAP protocol ships with the risk layer pre-written: a structural stop beyond the last 4-hour swing, size computed from it, the hold-to-the-end rule, and a grade (S or A) that decides whether a setup is traded at all. You still choose the risk fraction. Everything after it is arithmetic.
Watch my edge in 94 seconds→Can You Keep
the Account Alive?
15 questions on R, expectancy, the breakeven frontier, position sizing, leverage, Kelly, losing streaks, drawdown, correlation, costs in R and the exit ladder. Pick an answer and we will tell you exactly why it is right or wrong. No time limit.
Money Management
FAQ
What is money management in trading?
Money management is the set of rules that decide how much capital each trade may risk and how positions are sized, so that no single trade and no losing streak can do damage the account cannot recover from. Strategy decides what to trade and psychology decides whether you execute. Money management decides whether you are still trading after the losing run that every edge eventually produces.
What is the best money management strategy for trading?
For most traders: risk a small fixed fraction of current equity on each trade (1% is the common default, and many professionals work between 0.5% and 2%), size every position from where the stop has to go, cap the total risk open at once, and treat the Kelly criterion as a ceiling, never a target. The best books on it are Van Tharp’s Trade Your Way to Financial Freedom, which popularised R-multiples, and Ralph Vince’s The Mathematics of Money Management for the maths. This guide works through all of it in 17 diagrams, free, and the free calculator lets you test a size against a real trade record.
What is the 1% rule?
Risk no more than 1% of current account equity on any single trade, where risk is the distance from entry to stop multiplied by position size. At 1%, ten consecutive losses cost about 10% of the account. Many professionals work between 0.5% and 2%. Use current equity rather than starting equity, so the dollar risk shrinks in a drawdown.
How do you calculate position size?
Units = (account equity × risk %) ÷ (entry price − stop price). Place the stop first, at the level that invalidates the setup. Then divide the dollar risk by the per-unit distance to that stop. Example: $10,000 at 1% is $100 of risk; with an entry at 64,000 and a stop at 63,360 the distance is 640, so the size is 0.15625 BTC, a $10,000 position. Add costs in R on top.
Does leverage increase risk?
Not directly. On a sized trade, the loss if the stop fills depends only on position size and stop distance. Leverage changes how much margin the exchange holds and how close the liquidation price sits to entry. The danger is that high enough leverage moves liquidation inside the stop, so the position is closed out before the stop can work. Choose leverage only so the margin fits and liquidation sits well beyond the stop.
What is risk of ruin?
The probability that a run of losses reduces the account to a point it cannot recover from. It is driven mainly by risk per trade. The same ten-loss streak leaves about 90% of the account at 1% risk and about 6% at 25% risk. Because streaks are certain over a large sample, risk of ruin is a choice you make in advance through position size.
Why is a drawdown harder to recover from than the loss itself?
Because gains and losses are asymmetric. Recovery needed = 1 ÷ (1 − loss) − 1. A 10% loss needs +11%, a 50% loss needs +100%, a 75% loss needs +300%, because each recovery compounds from a smaller base. Avoiding a deep drawdown is far cheaper than climbing out of one.
What are R-multiples and expectancy?
An R-multiple expresses a trade's result as a multiple of the amount risked: risk $100 and make $300 and it is +3R. Expectancy is the average R per trade: (win rate × average win in R) − (loss rate × average loss in R). The published CAP backtest, 10,899 S and A grade trades after all costs, works out as 0.786 × 4.19R − 0.214 × 0.80R = +3.12R per trade, with a median trade of +1.53R.
What win rate do you need for a given risk-reward ratio?
Breakeven win rate = 1 ÷ (1 + payoff), where payoff is average win divided by average loss. 1:1 needs 50%, 2:1 needs 33.3%, 3:1 needs 25%, 5:1 about 16.7%, before costs. A system with a payoff below 1:1 can still be profitable if it wins often enough.
Should I use the Kelly criterion to size trades?
Use it as a ceiling, never a target. Kelly gives the fraction that maximises long-run growth when the edge is known exactly, but real edges are estimates, trades are correlated and losses have fat tails. Full Kelly carries roughly a one-in-two chance of the account halving at some point, half Kelly about one in eight. Most professionals size far below it.
How many losing trades in a row should I expect?
More than the arithmetic suggests. At the backtest's 21.4% loss rate a run of five or more should turn up in only about 3% of 100-trade stretches, yet one position at a time the worst version on Ethereum lost eight in a row and on Solana nine, because real trades are not independent: a bad stretch of market produces several losers together. Size for the streak you have not seen yet.
How much total risk should be open at once?
Set a cap on total open risk, often called portfolio heat, and test it against your worst drawdown. Count correlated positions, such as simultaneous longs in BTC, ETH and SOL, as one position for that cap, because they tend to fail together in a market-wide move.
What is the difference between money management and risk management?
They overlap. Risk management is the broader discipline of limiting every threat to capital, including leverage, correlation, counterparty and operational risk. Money management is its practical core: risk per trade, position size, open-risk caps and loss limits. In the CAP Framework both are pre-defined before a trade exists.
Master the Math
of Survival — Free
The full formula, fixed-fractional vs volatility-based sizing, and how to keep risk constant whether your stop is wide or tight.
Read the guide → Risk : RewardWhy a 1:3 trade only needs a 25% win rate, how to find asymmetric setups, and the breakeven-win-rate table every trader should memorise.
Read the guide → The ReasonBlown accounts are almost always a sizing problem, not an analysis problem. The risk habits that separate survivors from statistics.
Read the guide → Track Your RLog every trade in R, separate setup quality from execution, and watch your real expectancy emerge from the data over time.
Read the guide → Prove the EdgeBefore you size up, sample 100+ trades across regimes and measure expectancy in R and maximum drawdown — the numbers money management runs on.
Read the guide → The MindsetSizing only works if you can accept the pre-defined loss. The Stoic frame that makes risking 1% feel effortless and revenge-sizing impossible.
Read the guide →The other four pillars
of the curriculum.
Protect the downside.
The upside takes care of itself.
Every great trader is, first, a great risk manager. The CAP Framework bakes money management into the system: a structural stop, a fixed risk fraction, and position size computed before the trade exists. You stop guessing how much, and start compounding a positive expectancy you can actually survive.
Watch my edge in 94 seconds→